What determines the value of used technology equipment?
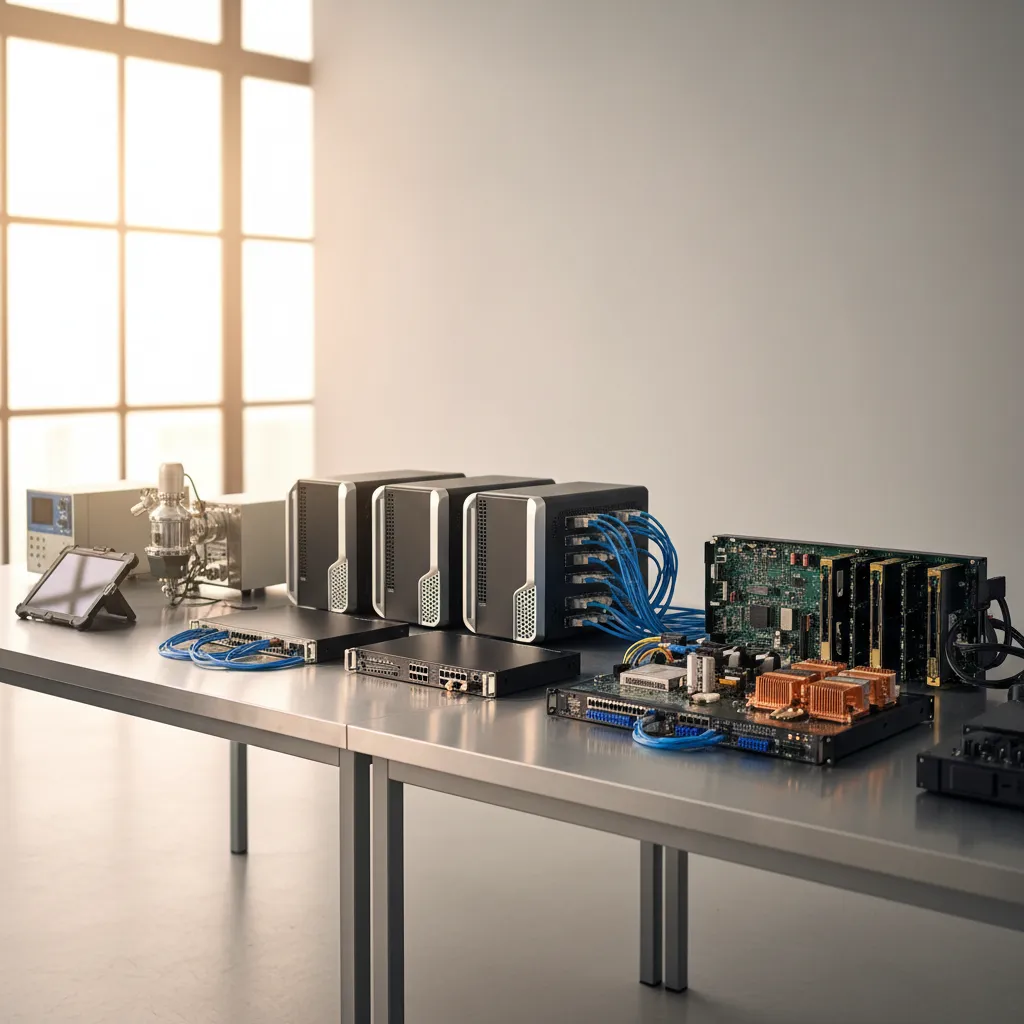
Configuration and condition details matched against real market evidence: dealer and reseller quotes for makes like Cisco, Dell, and HPE, IT asset auction results, and published used-equipment values, adjusted for age, remaining life, and obsolescence. Missing serials or incomplete specs, such as CPU, memory, storage, and options, force assumptions that weaken the conclusion, so asset-level documentation matters as much as the market data.
Which standard of value applies to technology equipment?
The one matched to the purpose. Fair market value, orderly liquidation value, forced liquidation value, actual cash value, and replacement cost new are all formally defined and produce different numbers: insurance typically uses actual cash value or replacement cost new, while lenders and bankruptcy matters call for FMV, OLV, or FLV depending on expected sale conditions. Mislabeling the standard can misstate value by tens of percent.
Why is technology equipment often worth less than its book value?
Because hardware loses market value faster than accounting schedules assume. When manufacturer support ends, performance is no longer competitive, or newer models are meaningfully more efficient, appraisers must take substantial functional obsolescence deductions. Relying on net book value overstates collateral and charitable values, and it leaves assets under-insured or deductions exposed.
How does a financial reporting appraisal treat tech equipment?
Under ASC 820 fair value rules, which give the greatest weight to observable market prices. When comparable sales or dealer quotes exist for current-generation hardware, the appraiser relies on those observable inputs rather than purely cost-based estimates. Only when the market is thin or the asset highly specialized does the analysis lean on replacement cost with obsolescence adjustments.