How do appraisers develop machinery values for Nevada businesses?
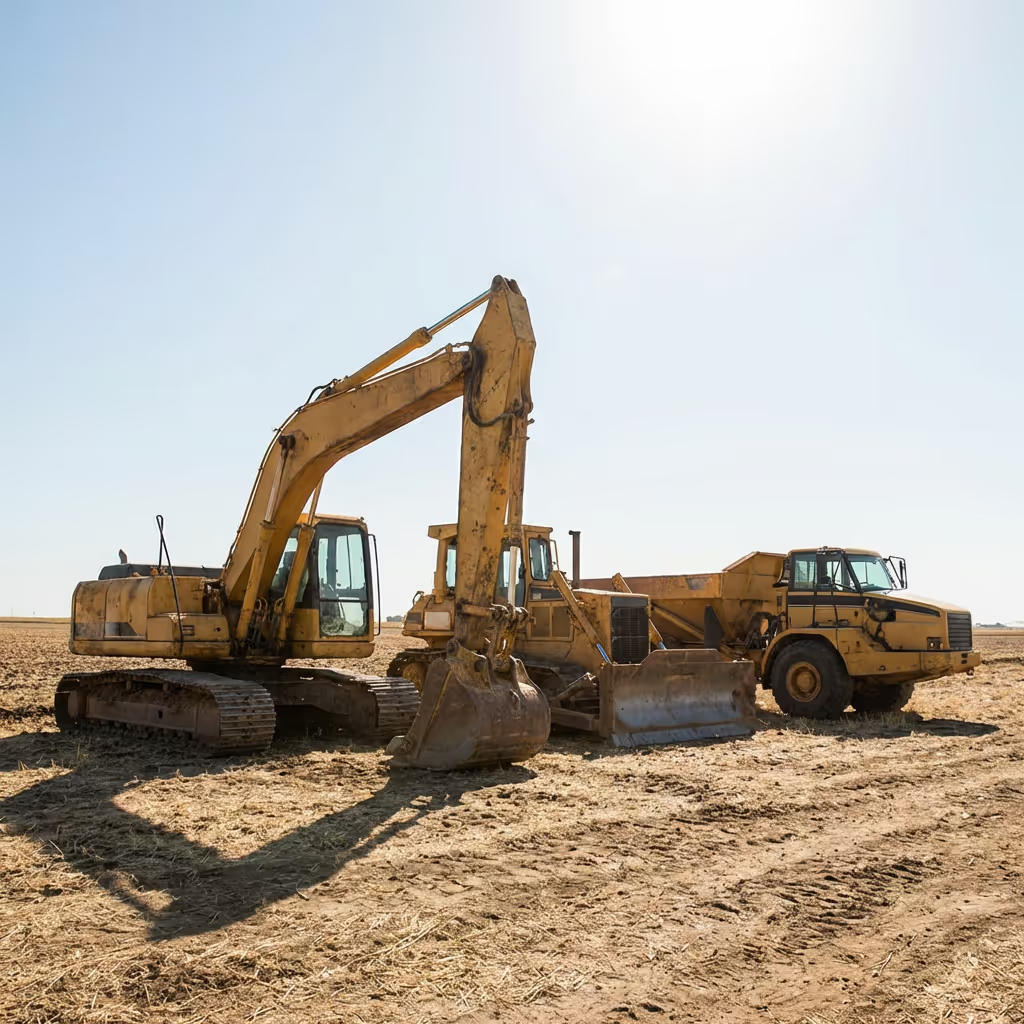
Primarily through the market and cost approaches. We compare your equipment to documented transactions from auction platforms like BidSpotter, IronPlanet, and MachineryTrader and adjust for age, hours, configuration, and location, then cross-check with a cost analysis that starts at current replacement cost and deducts physical, functional, and economic depreciation.
Is the assessor's taxable value the same as my equipment's market value?
No. Nevada's personal property tax system derives taxable value from acquisition cost, acquisition year, expected life, and a cost-conversion factor per the state's Personal Property Manual, with businesses filing annual declarations (due July 31 in Clark County). That formula-driven figure serves tax administration; it is not a substitute for a market-based appraisal when you are selling, financing, or litigating over equipment.
Can anyone appraise property for Nevada tax authorities?
No. NRS 361.221 bars a person from performing appraiser duties for the state or its political subdivisions without a valid appraiser's certificate from the Department; a noncertified employee may collect data, but a certified appraiser must review it. That rule governs government assessment work, while private equipment appraisals are judged on methodology and documentation.
Can a Nevada estate sell machinery without a current appraisal?
Generally not at private sale. NRS 148.170 bars the court from confirming a private sale of personal property unless the offer represents fair market value and the property was appraised within one year before the sale; otherwise a new appraisement is required, with waiver available only in narrow circumstances. A stale valuation can stall an estate sale.
Is any business equipment exempt from Nevada’s personal property tax?
Yes. NRS 361.068 exempts business inventories held for sale, consumable supplies, livestock, certain agricultural equipment and pipe, and fine art for public display, among other categories. Qualifying assets sit entirely outside the tax base, which changes the annual carrying cost picture for equipment-heavy operations.