01
Household Goods & Personal Property
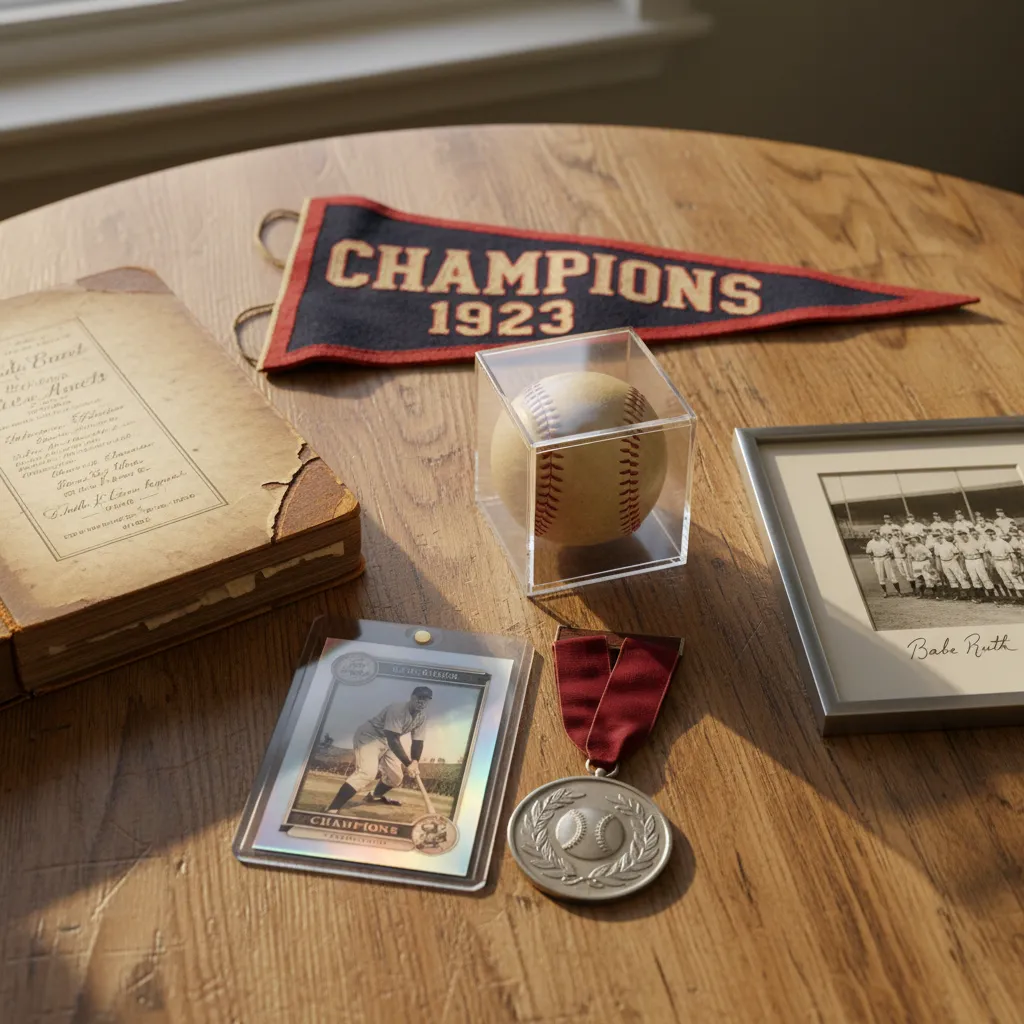
We appraise jewelry, furniture, antiques, firearms, and collections at the replacement cost your rider or contents coverage should carry, from a single scheduled piece to a whole household.
If you sent us a request between 28 July and 5 August, it did not reach us. A fault on our form stopped some messages from coming through. Please call (301) 820-7664 or fill the form again. We're sorry for the inconvenience.

Insurance coverage appraisal services establishing scheduled values for personal property, vehicles, and equipment before a loss occurs. AppraiseItNow appraises firearms, collectibles, motorcycles, and RVs for insurance scheduling.
These guys were phenomenal… I will definitely use them again
…they did a superb job and clearly explained how they arrived at the appraisal value
They negotiated with the insurance for us… Absolutely worth the price we paid
DEFENSIBLE, USPAP-COMPLIANT APPRAISAL REPORTS — QUALIFIED FOR INSURANCE CARRIERS, UNDERWRITERS, AND AGENTS.
01
We appraise jewelry, furniture, antiques, firearms, and collections at the replacement cost your rider or contents coverage should carry, from a single scheduled piece to a whole household.
02
We value paintings, prints, sculpture, and photography at retail replacement cost for fine art riders and agreed-value schedules, with the standard of value stated on the first page.
03
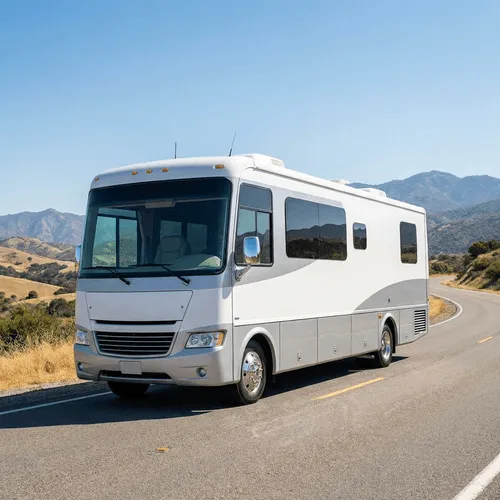
We document the value carriers ask for before writing agreed-value coverage on a classic car, custom motorcycle, boat, or RV, or the hull value a lender or marina requires.
04
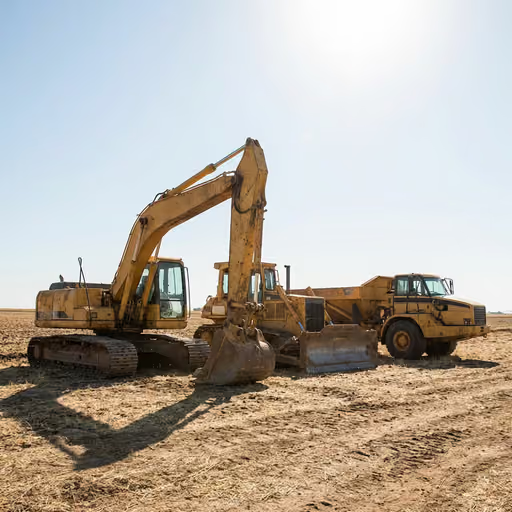
We establish replacement cost new and actual cash value for the machinery on a commercial policy, so the sum insured matches what it would take to replace it.

Owner & CEO
Joe founded AppraiseItNow to make a certified, USPAP-compliant appraisal as simple to order as anything else online. A former Bain & Company strategy consultant, Joe leads the entire team and specializes in strategy, growth, and the firm's tech capabilities.

Personal Property Appraiser
ISA Accredited Member with 30 years in the trade, from running estate sales and an auction gallery to appraising luxury apparel, furniture, artwork, antiques, and business assets, primarily for IRS tax filings.

Machinery & Equipment Appraiser
Third-generation auctioneer and CAGA Certified Appraiser with more than 20 years valuing machinery, equipment, vehicles, business assets, and estates for banks, attorneys, and trustees across the Carolinas.

Personal Property Appraiser
ISA Accredited Member specializing in Asian art, with a Master's from SOAS and a Postgraduate Diploma in Asian Art. Ashley chairs the ISA's Antiques, Furnishings, and Decorative Arts committee and appraises for charitable donation, insurance, and equitable distribution.

Vehicle Appraiser
CAGA Certified Appraiser since 2014, covering vehicles, boats, equipment, fine art, and collectibles. A classic-car restoration background informs her vehicle work, with reports prepared for insurance, divorce, and charitable contributions.
Business Valuation Expert & Appraiser
ASA, ABV, and CFA charterholder. Since 2016 Justin has valued businesses for estate and gift tax, purchase price allocations, fairness opinions, lending, and buy-sell agreements, across manufacturing, services, retail, and pre-revenue biotech.
Business Valuation Expert & Appraiser
Accredited Senior Appraiser with the American Society of Appraisers. Raymond values capital stock, business enterprises, stock options, and intangible assets.

Client Success Manager
Manages each engagement from the first enquiry to the delivered report, and keeps you posted at every step along the way.
 International Society of AppraisersAccredited Member
 Certified Appraisers Guild of AmericaCertified Appraiser
 American Society of AppraisersAccredited Senior Appraiser
 The Appraisal FoundationAuthorized by Congress as the source of appraisal standards
A policy pays on the standard of value printed in it, and the three can differ by the full amount of depreciation. Before we value anything we confirm which one your carrier or agent needs, and the report names it on the first page so the underwriter is reading the number they asked for.
What it would cost to buy a comparable item at retail today, with nothing deducted for age or wear. On this basis the insured value usually includes the dealer markup, buyer’s premium, and tax a real replacement would carry, which is why it runs above the fair market value used on tax filings.
Policies are typically written on this basis for:
Replacement cost less depreciation, or the item’s market value immediately before a loss; which of the two applies depends on the policy wording and the state. It is the default basis for unscheduled contents under a standard homeowners form and for most vehicle and boat policies.
Policies are typically written on this basis for:
A value fixed on the declarations page when the policy is written and paid in full on a total loss, with no negotiation over depreciation afterwards. Carriers ask for an appraisal, photographs, and build or provenance records before they agree to it.
Policies are typically written on this basis for:
Bars are illustrative and imply no figure. The depreciation an actual cash value policy deducts, and the amount a carrier will agree to, are findings of the assignment.
Before a loss
Establishes the value your limits, schedules, and agreed amounts are built on, so the policy is right before anything happens.
This page
After a loss
Establishes what was lost and what it costs to replace, and supports a dispute under the policy’s appraisal clause.
Insurance claim appraisalsWe confirm the standard your carrier or agent needs before work begins, quote a flat fee up front, and write every report to USPAP.
What you receive
Scheduling an item moves it from a category sublimit to coverage at its declared value, and carriers ask for support before they schedule it. The report is that support: the identifiers, condition, market evidence, and stated value standard an underwriter checks, listed piece by piece where a rider calls for it and by category on a large contents or equipment assignment.
Values withheld. A scheduled piece is listed with its identifiers, condition, the basis of value the policy names, and the appraised amount; a large assignment groups by category, with the depth of documentation agreed before work begins.
Make, model, and serial number; maker, medium, and dimensions; VIN or hull number. The identifiers that tie the line to the object.
Photographs and a condition note for the pieces being scheduled. On a large contents or equipment assignment the depth of documentation is agreed up front, and categories are treated as categories.
Comparable retail sales, dealer and auction records, and recognized guide values for vehicles and boats, cited in the report.
Replacement cost, actual cash value, or agreed value, named on the first page with the intended use, so the underwriter is reading the basis they asked for.
A signed USPAP certification from an appraiser holding credentials with organizations such as the ASA, ISA, or AAA.
An insurance coverage appraisal is the right step when:
Turnaround varies by project. Tell us the binding or renewal date and we confirm up front whether we can meet it.
What insurance coverage clients say we are known for
Across 17 published insurance coverage appraisal reviews, every one from a client who paid AppraiseItNow for an appraisal, the three things they raise most often are that they would hire us again, how much research is visible in the report, and how quickly we answer.
These guys were phenomenal. Joe was very responsive and gave clear instructions on how to submit my information for the appraisal, which he completed in a very quick timeframe. The appraisal itself was extremely detailed and included a thorough explanation of how they arrived at the value. It came with extensive documentation, and it’s clear they did a significant amount of research. They were also very responsive through text and email and always available to answer any questions. I had them appraise my fifth-wheel RV for resale, and I highly recommend their services. I will definitely use them again.
Recreational Vehicle Appraisal for Insurance Coverage
The appraisal was done very well. Since he was a local artist here in Charleston, SC, they took the time to study and review Jim Booth’s art. His work has made him extremely famous, which can make an appraisal challenging, but they did a superb job and clearly explained how they arrived at the appraisal value. I highly recommend Appraise It Now and will use them again for all my artwork.
Artwork Appraisal for Insurance Coverage
AppraiseItNow did an excellent job appraising our unique art collection. Joe was always prompt and responsive, and he and his team delivered a thorough, well-supported appraisal in just a couple of weeks, even during the holiday season. I was genuinely impressed. Thank you for the great work!
Artwork Appraisal for Insurance Coverage
AppraiseItNow's service was expeditious and professional. The report was thorough with plenty of examples and rationale for the valuations. Good service comes at a cost, but for me it was well worth it. Highly recommended!
Personal Property Appraisal for Insurance Coverage
We recently used AppraiseItNow for one of our clients and couldn’t be happier with the experience. The customer service was excellent, and Joe was quick to respond to all of our questions. He provided everything we needed promptly and made the process smooth from start to finish. Thank you!
Boat Appraisal for Insurance Coverage
I was looking for an appraisal and time was of the essence. They got the job done in only a few days with excellent customer service. Great business to work with.
Machinery & Equipment Appraisal for Insurance Coverage
AppraiseItNow offers online appraisals and onsite appraisals in all 50 states.
No. Insurance coverage appraisals are not tax events and do not require IRS forms such as Form 8283, which applies only to charitable donations of non-cash property exceeding $5,000. Your appraisal report is prepared for insurer submission and retention, not for tax filing purposes.
Only up to a category sublimit. Standard homeowners forms cover contents as a percentage of the dwelling limit and cap unscheduled categories such as jewelry, firearms, and collectibles at modest per-category amounts, often a few thousand dollars, whatever the collection is actually worth. Scheduling an item on a rider moves it to coverage at its declared value, and carriers usually ask for an appraisal before they schedule it.
Yes. Carriers writing agreed-value coverage on classic and custom vehicles, boats, and vintage RVs ask for an appraisal with photographs and build or restoration records, and the agreed figure then becomes the total-loss payout with no depreciation deducted afterwards. We document the vehicle or the hull, including the engines, electronics, and equipment a boat’s hull value includes, and state the standard of value the carrier names.
If your policy limits no longer reflect the current replacement cost of your assets, you risk being underinsured at the time of a claim. Periodic appraisal updates ensure your coverage keeps pace with market conditions, new acquisitions, and changes to existing assets.
That is the insurer’s decision, and we never promise it. Our reports are written to USPAP, state the value standard your policy uses (replacement cost, actual cash value, or agreed value), and carry the identifiers, photographs, and market evidence underwriters ask for. If your carrier has a specific wording or form requirement, tell us before we begin and we write to it; checking with your agent first avoids a revision later.
No. An insurance coverage appraisal establishes replacement value before a loss to set adequate policy limits. Post-loss claim appraisals address disputes over the amount of a loss, while questions about whether a loss is covered at all are matters of policy interpretation handled outside the appraisal process.