When you're seeking financing from a bank, understanding the loan appraisal process can make the difference between approval and rejection. A loan appraisal is a professional assessment that determines the fair market value of assets you're pledging as collateral, helping lenders evaluate their risk and set appropriate loan terms.
Most secured loans require an appraisal to verify that your collateral has sufficient value to protect the lender's investment. This process typically takes 1-2 weeks for residential properties and can influence your interest rate, loan amount, and approval odds. Whether you're using real estate, vehicles, or business assets as collateral, knowing what to expect helps you navigate the financing process with confidence.
Key insight: Banks typically lend 70-80% of an asset's appraised value, meaning a higher appraisal directly translates to more available financing.
Understanding loan appraisals and collateral basics
A loan appraisal is essentially a professional opinion of value conducted by a certified appraiser. When you apply for a secured loan, the bank needs to know exactly what your collateral is worth in today's market. This isn't just about what you paid for the asset or what you think it's worth - it's about what a qualified buyer would realistically pay in current market conditions.
Collateral serves as the bank's safety net. If you default on your loan, they can seize and sell the asset to recover their losses. That's why they're so particular about getting an accurate valuation. The appraiser will examine factors like condition, location, comparable sales, and market trends to arrive at a fair market value.
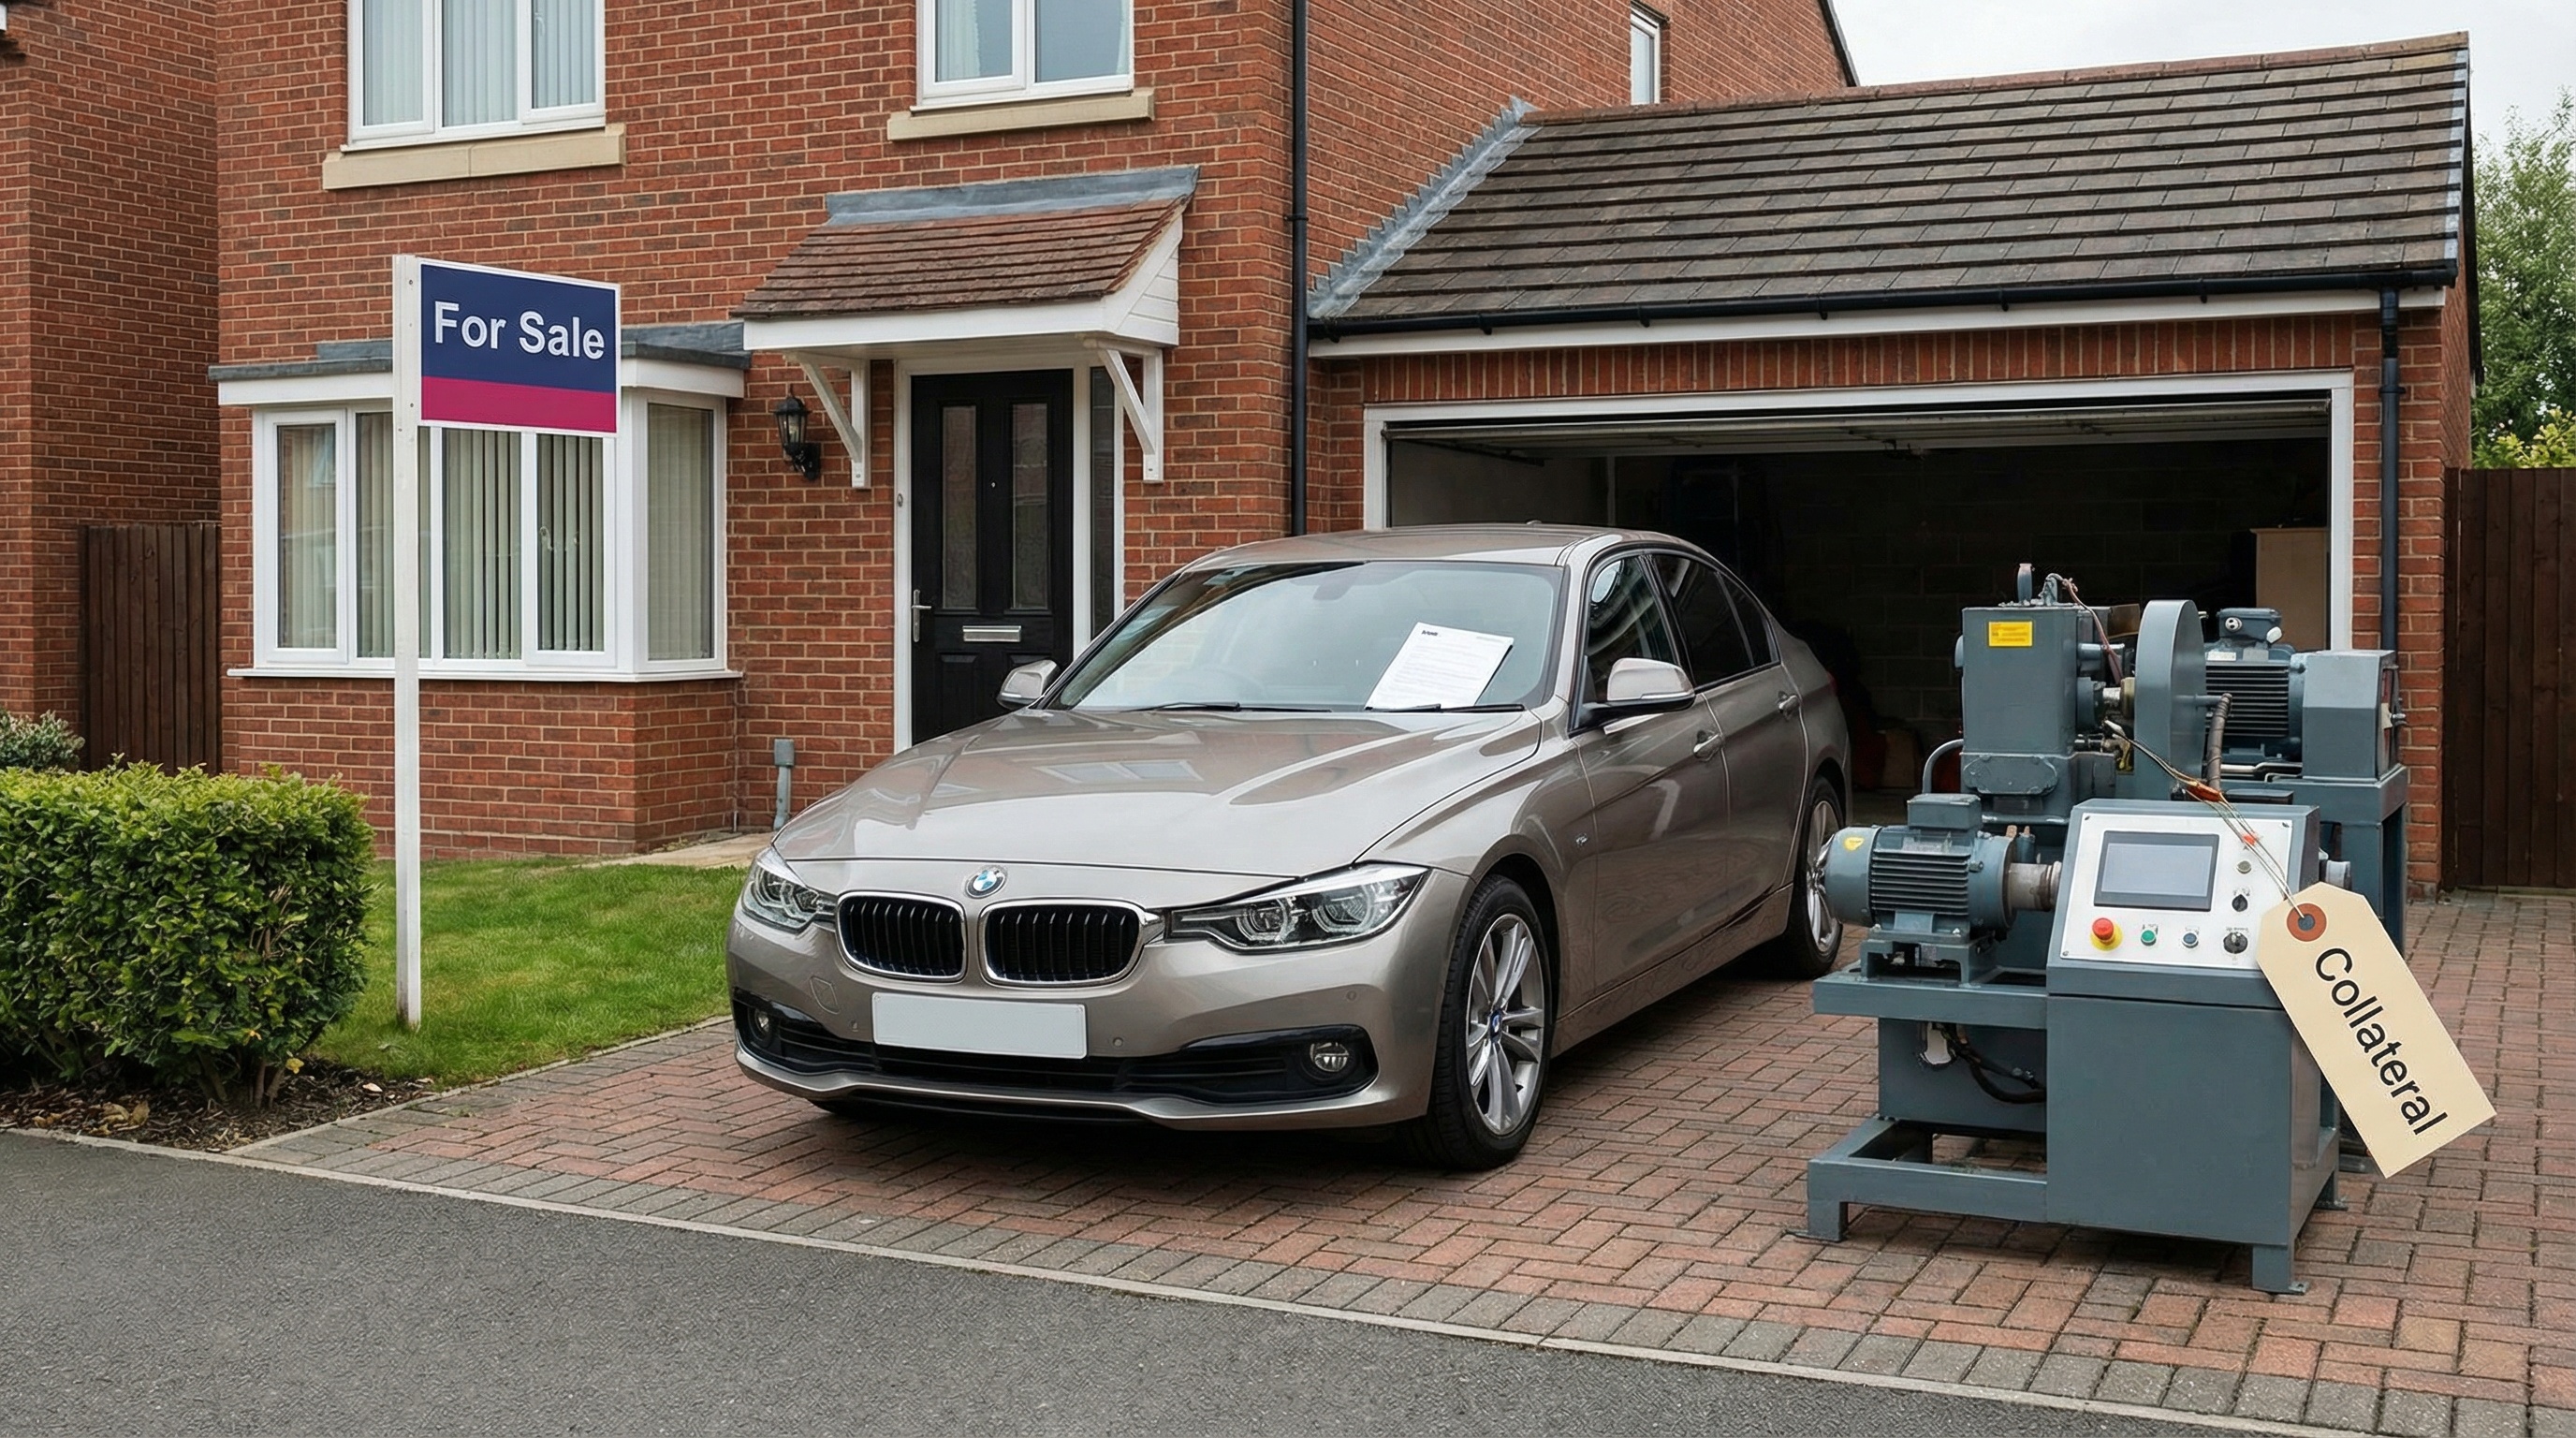
Not every asset qualifies as acceptable collateral. Banks typically prefer assets that are easy to value, have stable market demand, and can be quickly liquidated if necessary. Real estate, vehicles, and established business equipment usually make the cut, while highly specialized or rapidly depreciating items might not.
Types of assets accepted for loan collateral
Banks have specific preferences when it comes to collateral, and understanding these can help you choose the right asset to secure your financing. Real estate consistently ranks as the most preferred collateral because property values tend to be stable and predictable. Whether it's your primary residence, investment property, or commercial real estate, these assets typically qualify for the most favorable loan terms.
Vehicles represent another common form of collateral, though banks are more selective here. Cars, trucks, boats, and recreational vehicles can work, but lenders often set age and mileage limits. A five-year-old sedan in good condition will be more attractive than a fifteen-year-old vehicle with high mileage.
Business assets like equipment, inventory, and machinery can also serve as collateral, particularly for commercial loans. However, banks scrutinize these more carefully because their value can fluctuate based on industry conditions and technological changes. They'll want detailed records of maintenance, age, and current market demand for your specific equipment. Understanding types of business assets that need appraisal can help you prepare for this process.
Important note: Some banks won't accept collectibles, artwork, or highly specialized equipment as collateral due to valuation challenges and limited resale markets.
Financial assets like stocks, bonds, and certificates of deposit are generally welcomed as collateral because their values are easily tracked and they can be quickly liquidated. However, volatile investments might require larger equity cushions to account for potential value swings.
The loan appraisal process step by step
The appraisal process begins once your loan application moves forward and the bank determines they need a professional valuation. Typically, the lender orders the appraisal and selects the appraiser, though you'll usually pay the fee upfront or at closing.
For real estate appraisals, the appraiser will schedule a property visit to conduct a thorough inspection. They'll measure rooms, note the condition of major systems, document any improvements or issues, and take photographs. This physical inspection usually takes 30-60 minutes for a typical home.
| Asset Type | Typical Timeline | Inspection Required | Average Cost |
|---|---|---|---|
| Residential Property | 7-10 days | Yes | $400-$600 |
| Commercial Property | 2-3 weeks | Yes | $1,500-$5,000 |
| Vehicles | 3-5 days | Usually | $200-$400 |
| Business Equipment | 1-2 weeks | Yes | $500-$2,000 |
After the inspection, the appraiser researches comparable sales, analyzes market trends, and prepares a detailed report. This document includes their methodology, the factors they considered, and their final opinion of value. The entire process from ordering to receiving the completed appraisal typically takes 7-14 days for residential properties, though complex commercial appraisals can take several weeks. If you're dealing with business assets, learning how to prepare for a business asset appraisal can streamline this timeline.
Benefits and considerations for borrowers
Using an appraisal for your loan application offers several advantages beyond just meeting the bank's requirements. A professional appraisal provides you with an objective, third-party assessment of your asset's value, which can be valuable for insurance purposes, tax planning, or future financial decisions. The impact of an accurate appraisal on your investment extends far beyond the immediate loan transaction.
When your collateral appraises for more than expected, you might qualify for a larger loan amount or better interest rates. Banks view well-appraised, valuable collateral as lower risk, which often translates to more favorable terms for you. This can save you thousands of dollars over the life of your loan.
However, there are potential downsides to consider. If your asset appraises for less than you anticipated, it could limit your borrowing capacity or require you to provide additional collateral. The appraisal fee is typically non-refundable, even if your loan application is ultimately denied.
Pro tip: You can often expedite the appraisal process by ensuring your property is clean, accessible, and all necessary documentation is readily available when the appraiser arrives.
It's worth noting that the appraised value doesn't guarantee loan approval. Banks consider multiple factors including your credit score, income, debt-to-income ratio, and employment history. The appraisal is just one piece of the puzzle, albeit an important one. For those considering using business assets as collateral, getting the most out of your business asset appraisal requires strategic preparation.
Understanding the loan appraisal process empowers you to make informed decisions about your financing options. Whether you're buying a home, expanding your business, or consolidating debt, knowing what to expect from the appraisal can help you prepare effectively and increase your chances of securing the financing you need on favorable terms. Remember that while the process might seem complex, it's designed to protect both you and the lender by ensuring everyone has a clear understanding of the collateral's true value. If you're working with business assets specifically, consulting resources on understanding appraising business assets can provide additional clarity throughout the financing journey.