
Residential Personal Property Replacement-Cost Appraisal for Insurance Claim
Replacement cost appraisal for a residential insurance claim, covering furniture, linens, kitchenware, small electronics and accessories catalogued room by room. AppraiseItNow appraised a California household claim across bathroom, bedroom, closet, kitchen and linen spaces, identifying mid-tier retail equivalents for discontinued models under ISA and USPAP reporting standards.
Project Overview
Assignment Summary
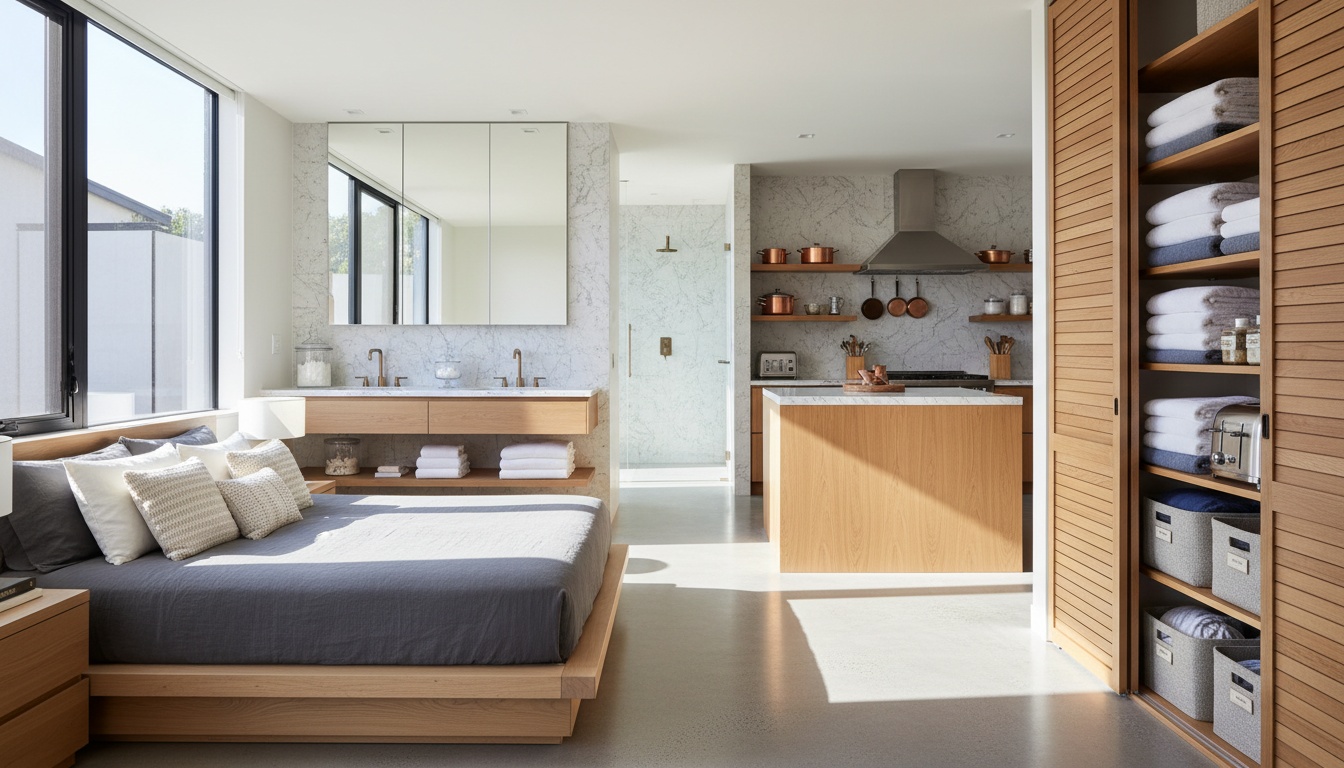
The scope of work required establishing replacement-cost values for personal property appraisal services within specific rooms of a residence for use in an insurance reimbursement claim. Subject assets included common household items such as furniture, linens, kitchenware, small electronics, and accessories distributed across the bathroom, bedroom, coat closet, kitchen, and linen closet. The appraisal was prepared in conformance with USPAP reporting standards and ISA guidance, employing the replacement-cost approach as the primary valuation method. The intended use was strictly for reimbursement and replacement planning. Deliverables included representative photographs, detailed line-item descriptions with brand and model information where available, unit prices with applicable taxes and delivery charges, room subtotals, and an aggregated replacement estimate.
Challenges
Our Approach
Project Outcome
Ready to start your appraisal?
Tell us the asset and what the value is for, and we will confirm scope, timing, and a fixed fee before any work begins.
Request an AppraisalFrequently Asked Questions
What replacement venue should a contents claim use?
The venue an average consumer would reasonably use to replace the item, not the cheapest source available and not a luxury retailer. That standard keeps the schedule defensible in both directions: it prevents a carrier from pricing replacements at clearance and prevents a claim from being built on aspirational substitutes. The report names the sources used for each line.
How are mid-tier equivalents chosen for items with no brand information?
By matching function, size, material and apparent quality tier, then selecting a current product that a reasonable buyer would treat as comparable. Many household items carry no identifiable brand, and insisting on exact matches would stall a claim indefinitely. The substitute is named in the schedule so the adjuster can accept or challenge that specific choice.
Why is a claim organized by room?
Because that is how the loss occurred and how the adjuster verifies it. A room-by-room schedule can be reconciled against the loss report, photographs and the policyholder's own recollection, which speeds review. It also surfaces omissions: an empty line for a room the policyholder described is easier to catch than a missing item in an alphabetical list.
What is the difference between an ISA-standard report and a general appraisal?
The International Society of Appraisers sets reporting practice for personal property work in addition to USPAP compliance, covering how items are described, how markets are identified and how conclusions are documented. For contents claims the practical effect is a more structured schedule with a stated market level per item, which is what carriers reviewing a large claim expect to see.