
Large Personal Property Appraisal for Charitable Donation
Estate collection appraisal for charitable donation substantiation, covering attributed artworks, vintage and midcentury furniture, hand-knotted and tribal rugs, decorative objects and extensive tableware. AppraiseItNow appraised a large California donation lot by lot from donor images and inventory records, preparing the appraiser's portion of IRS Form 8283 for the filing.
Project Overview
Assignment Summary
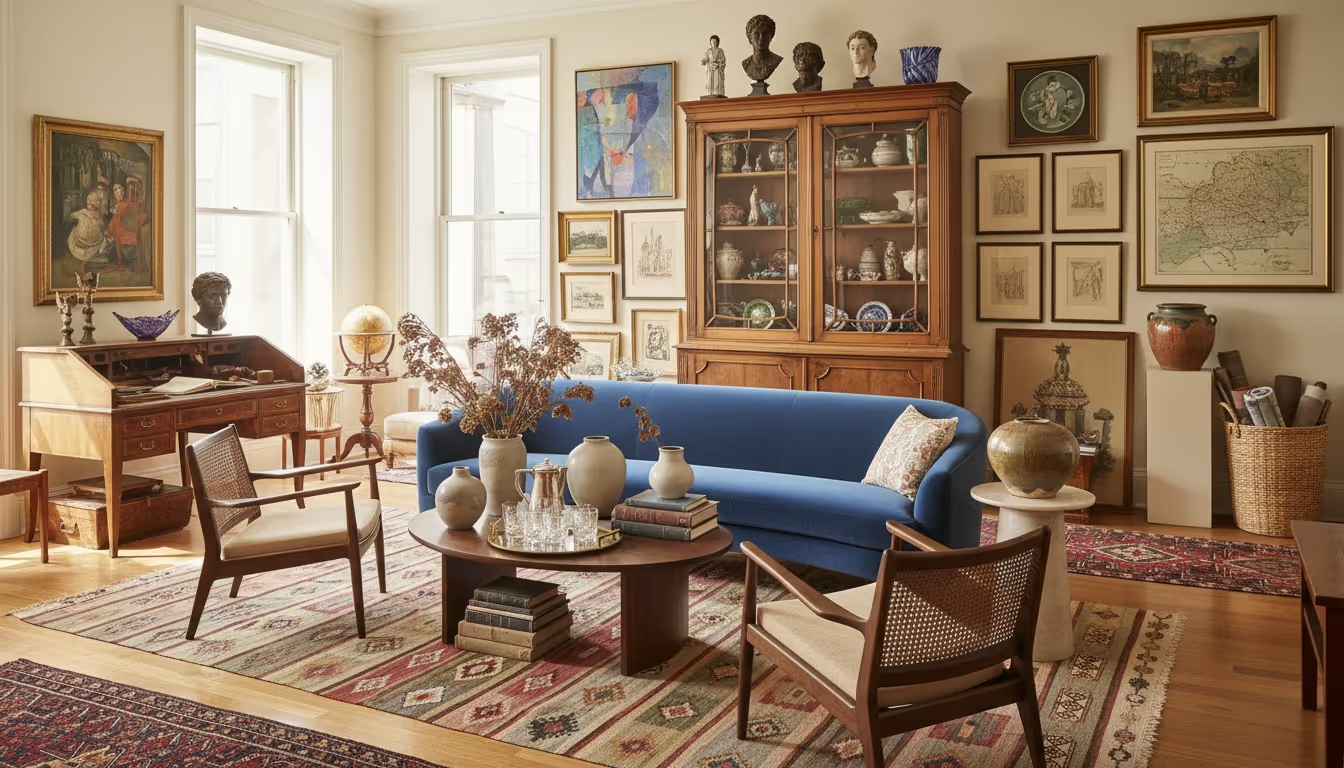
The appraiser examined a collection of personal property appraisal services via donor-supplied digital photographs and inventory information, identifying individual lots across several categories including works attributed to known artists, vintage and midcentury furniture, hand-knotted and tribal rugs, decorative objects, and extensive kitchen and tableware collections. The intended use was a qualified appraisal for a non-cash charitable contribution, and the report was developed to satisfy IRS substantiation requirements, including preparation of the appraiser's portion of Form 8283. The sales comparison approach was used to determine fair market value for each item and the collection as a whole, and the report followed USPAP's Appraisal Report option while citing applicable IRS publications and Treasury regulations relevant to charitable contribution valuations.
Challenges
Our Approach
Project Outcome
Ready to start your appraisal?
Tell us the asset and what the value is for, and we will confirm scope, timing, and a fixed fee before any work begins.
Request an AppraisalFrequently Asked Questions
How is a large mixed collection organized for a donation appraisal?
By category, because each category has its own market, its own comparables and its own condition vocabulary. Artworks, rugs, furniture and tableware are researched separately and reported separately, with individually significant pieces itemized and lower-value material grouped. That structure is what lets a reviewer test one part of the conclusion without unpicking the whole report.
What does works attributed to a known artist mean in an appraisal?
It means the evidence points to that artist but authorship has not been independently confirmed. Attributed is a deliberate term with a lower certainty than a firm attribution, and it carries a lower value. Where the donor's information supports attribution and no authentication exists, the report says attributed and prices accordingly rather than upgrading the claim.
How are hand-knotted rugs valued in a donated collection?
By origin, age, weave structure, dye type, size and condition, with condition weighing heavily: wear to the pile, ends and selvedges, repairs and any dry rot move a rug between very different price tiers. Tribal and village weavings are valued in a different market from workshop carpets. Photographs of the back and of any damage matter as much as images of the face.
What is the appraiser's role on Form 8283 for a large donation?
We complete and sign the Declaration of Appraiser in Section B and provide the appraisal that supports the reported figures. The donee signs the acknowledgment. For claimed values above $500,000 the appraisal itself must be attached to the return rather than summarized, which is worth knowing before a large collection is transferred.