
Industrial Hydraulic Hose Inventory Appraisal for Charitable Donation
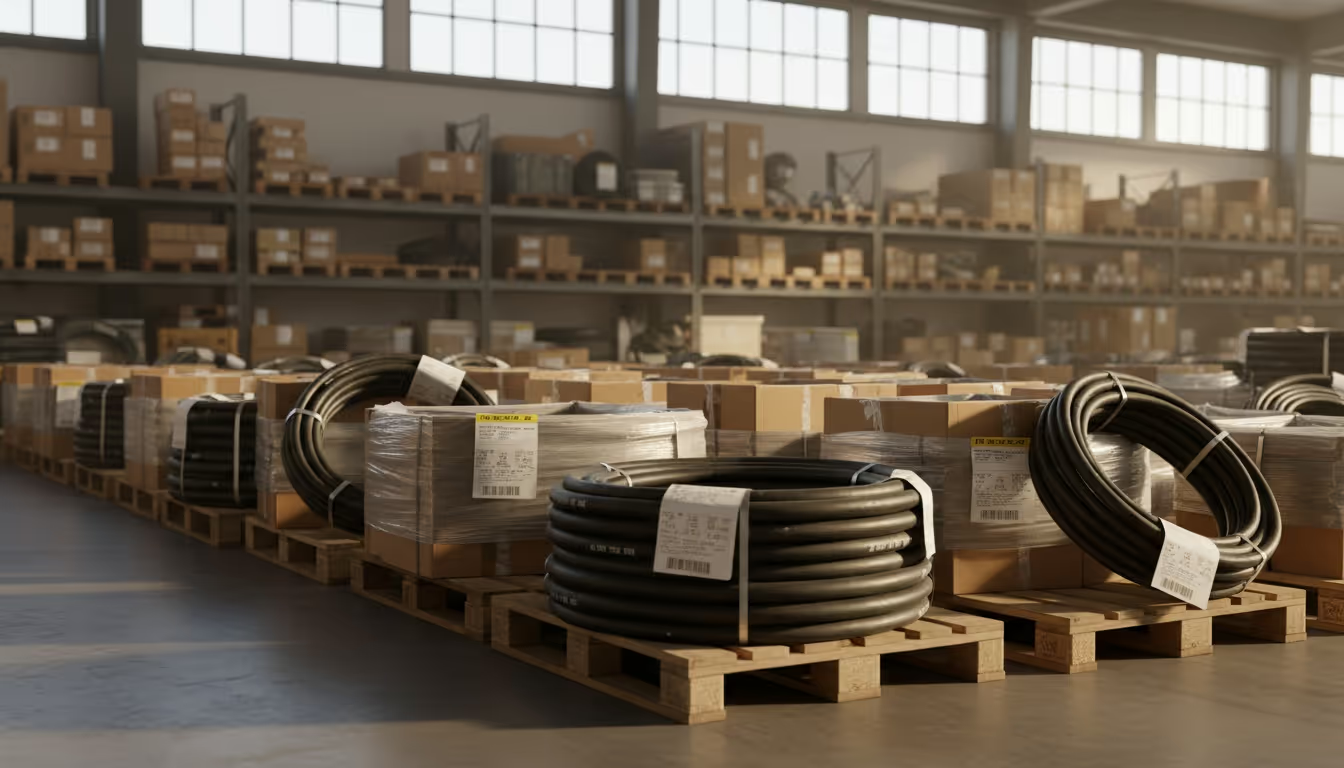
Hydraulic hose inventory appraisal for charitable donation substantiation, covering new-old-stock industrial hose, palletized bulk quantities and material without full distribution traceability. AppraiseItNow appraised a Texas donation of roughly 50 pallets of two-wire, flame-resistant hydraulic hose, researching the secondary industrial market where untraceable stock actually resells.
Project Overview
Assignment Summary
The scope encompassed identification and description of approximately 50 pallets of new-old-stock, two-wire, high-pressure hydraulic hose with flame-resistant and anti-static properties designed for industrial applications. Using representative photographs and documentation provided by the donor, our appraisers conducted a thorough condition assessment, researched comparable sales in secondary industrial markets, and developed a fair market value opinion specifically for charitable contribution purposes. The assignment employed the sales comparison approach to capture actual resale behavior rather than theoretical replacement cost. The intended users were the donor and tax authorities, and all work was performed in full compliance with USPAP and relevant IRS substantiation requirements for non-cash contributions.
Challenges
Our Approach
Project Outcome
Ready to start your appraisal?
Tell us the asset and what the value is for, and we will confirm scope, timing, and a fixed fee before any work begins.
Request an AppraisalFrequently Asked Questions
Why does missing traceability reduce the value of new industrial stock?
Because certified distribution channels will not take it. Buyers of hydraulic hose for pressure-critical applications require manufacturer traceability and warranty coverage, and material without that documentation is excluded from the authorized channel regardless of its physical condition. It moves instead through surplus and secondary industrial resellers at a substantial discount, and that is the market the valuation uses.
Is new-old-stock the same as new for valuation purposes?
No. New-old-stock is unused but aged, and for rubber goods age matters: elastomers degrade over time even in storage, and specifications and standards move on. Buyers price that risk. The analysis reflects the age of the stock and any shelf-life considerations rather than treating unused as equivalent to current production.
How is a 50-pallet donation valued without counting every foot?
By establishing the packaging configuration and pallet content from documentation and representative photographs, then extending a verified per-unit rate across the confirmed count. The report shows the unit basis and the extension so a reviewer can check the arithmetic. Where pallet contents could not be individually verified, that is stated rather than implied.
Does the charity's ability to use industrial material affect the appraisal?
Not the value conclusion, which reflects the market rather than the donee. It can affect the donor's deduction through the related use rule for tangible personal property, and it affects credibility: a donation of specialized industrial stock to an organization with no use for it invites the question of what the charity would actually realize. The appraisal reports market value; the donor's advisor applies the rules.