
Charitable Donation Appraisal of Lithographic Reproductions
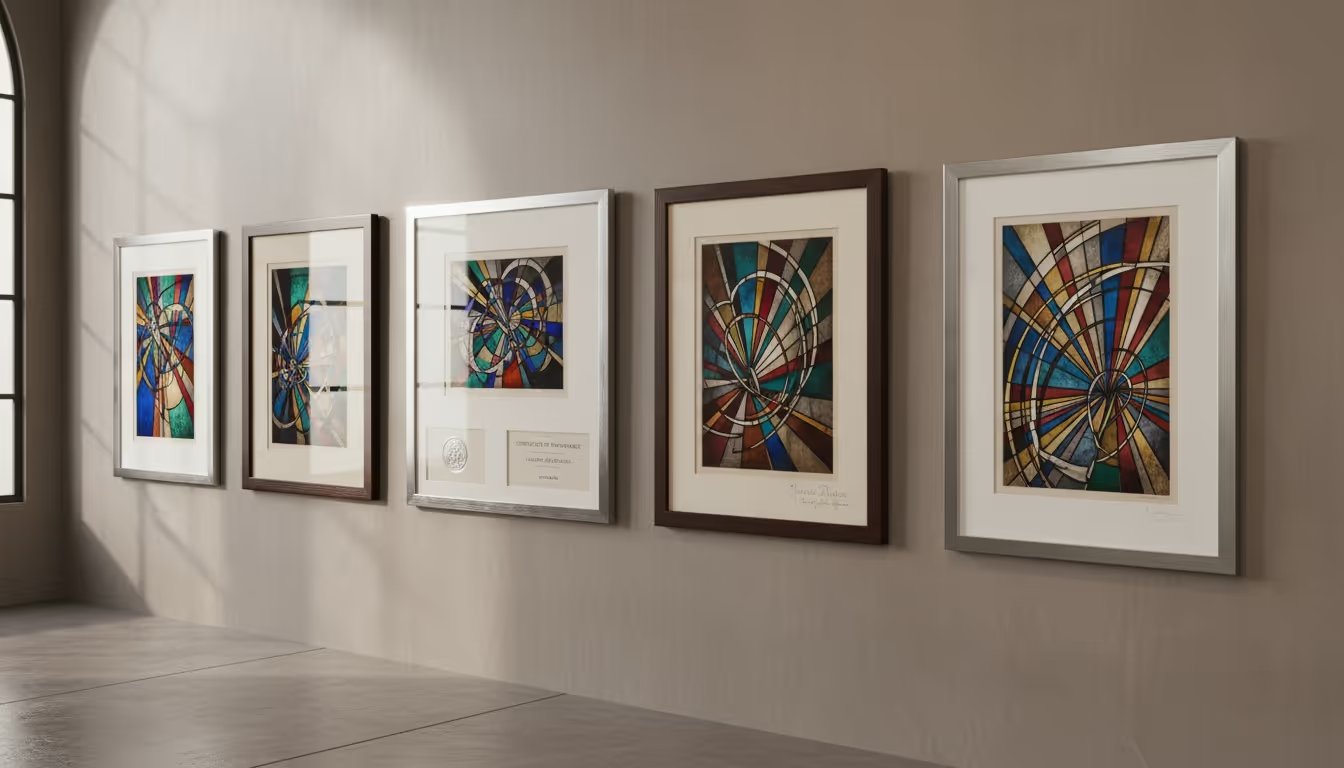
Lithograph appraisal for charitable donation substantiation, covering later reproductions, posthumously signed impressions, and framed prints without edition numbering. AppraiseItNow appraised a North Carolina donation of five framed lithographs reproducing stained-glass imagery by a noted modern artist, establishing that they were later reproductions rather than original limited editions.
Project Overview
Assignment Summary
The scope covered identification and description of five framed lithographs reproducing stained-glass imagery by a noted modern artist. These pieces appeared to be later reproductions rather than original limited edition prints, with characteristics including post-mortem pencil signatures, different paper types, and lack of edition numbering. We examined the items remotely using high-quality photographs and provenance documentation provided by the donor, noting generally good condition throughout. The appraisal was structured to conform to both USPAP and Treasury/IRS requirements for non-cash charitable contribution appraisals, utilizing the certified art appraisal report format. We applied the sales comparison approach to determine fair market value by analyzing recent market transactions of comparable reproductions and gallery offerings. One piece was accompanied by a gallery certificate, while others displayed characteristics that placed them in a different market tier than original limited editions.
Challenges
Our Approach
Project Outcome
Ready to start your appraisal?
Tell us the asset and what the value is for, and we will confirm scope, timing, and a fixed fee before any work begins.
Request an AppraisalFrequently Asked Questions
How can you tell an original limited edition print from a later reproduction?
The tells are physical and documentary: edition numbering, the paper stock and its watermark, plate or stone characteristics, the printer's marks, and how the signature was applied. A pencil signature applied after the artist's death, paper inconsistent with the original edition, and the absence of any edition number together point to a reproduction. Each of those observations is recorded in the report because the classification drives the value.
What does a posthumous signature do to value?
It generally removes the work from the original print market entirely. Impressions signed after an artist's death are not autograph works, and the collectors who pay for original editions do not treat them as substitutes. The relevant market becomes decorative reproductions, where prices are a small fraction of the original edition. Reporting the two as equivalent is the single largest valuation error in this category.
Why does correct classification matter more than condition for prints?
Because the classification determines which market applies, and the gap between markets is far larger than any condition adjustment within one. A pristine reproduction is worth less than a worn original impression. Condition is assessed and does affect the conclusion, but only after the work has been placed in the right category.
What should a donor provide when donating framed prints?
Documentation that helps establish what the works are:
- Purchase invoices or gallery receipts, with dates
- Any certificates, gallery labels or verso inscriptions, photographed
- Clear images of the full sheet including margins and any numbering
- Images of the signature at high magnification
- Any prior appraisals or insurance schedules covering the works