
Business Inventory Appraisal for Charitable Donation
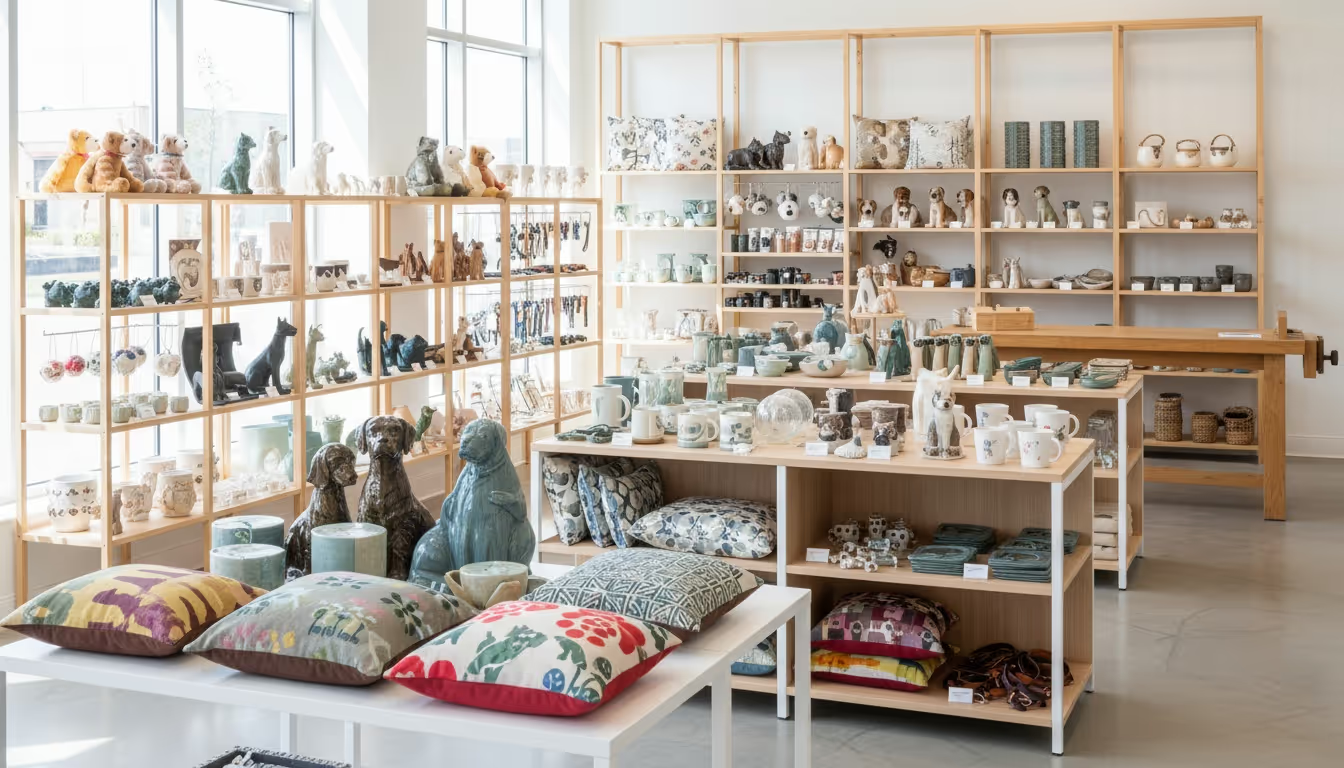
Retail inventory appraisal for charitable donation substantiation, covering multi-SKU stock, decorative and functional consumer goods, and handmade merchandise held for sale. AppraiseItNow appraised a California donation of pet-themed retail goods and handmade decorative statues, categorizing several thousand units by product type and valuing them in the market where that volume would actually move.
Project Overview
Assignment Summary
The scope covered identification, condition assessment, market research, and valuation of a large, multi-SKU retail inventory for charitable donation substantiation. Subject assets were categorized by product type, including decorative and functional pet-themed retail goods and handmade decorative statues, and evaluated as tangible personal property. Valuation was developed in conformance with USPAP and applicable IRS guidance for non-cash contributions, with the report documenting the methods, assumptions, and supporting market data. The appraiser prepared an Appraisal Report and completed the signed portion of IRS Form 8283 to assist with the donor's filing requirements.
Challenges
Our Approach
Project Outcome
Ready to start your appraisal?
Tell us the asset and what the value is for, and we will confirm scope, timing, and a fixed fee before any work begins.
Request an AppraisalFrequently Asked Questions
Why is donated retail inventory not valued at its shelf price?
Retail price is what one unit sells for to one consumer, and a donation transfers the whole lot at once. The relevant market for a multi-SKU donation is the channel that absorbs that quantity, which is normally wholesale or secondary liquidation. Using shelf pricing on thousands of units assumes a retail demand curve that the donation itself never touches, and it is one of the most common reasons an inventory appraisal fails review.
How are thousands of SKUs handled without valuing each one individually?
Items are grouped into categories that behave the same way in the market, then valued at the category level with representative comparables and unit counts. Higher-value or distinctive SKUs are pulled out and treated individually. The report documents the grouping logic so a reviewer can follow how a line on the inventory sheet became a line in the value conclusion.
Is the deduction for donated inventory limited to what the business paid for it?
Often, yes. Inventory is ordinary income property, and Internal Revenue Code section 170(e) generally limits the charitable deduction for such property to the donor's cost basis rather than fair market value, with narrow exceptions. The appraisal establishes fair market value; how that figure interacts with the basis limitation is a determination for the donor's tax advisor, and it should be settled before the return is filed.
What does the appraiser sign on IRS Form 8283?
For noncash contributions over $5,000 the appraiser completes and signs the Declaration of Appraiser in Section B, Part IV, and the donee organization signs the acknowledgment. We complete our portion as part of the engagement. The signature attests to the appraiser's qualifications and independence, which is why it cannot be provided by anyone with an interest in the donated property.