Alabama Business Valuation

5.0from 100+ client reviews

Business valuations in Alabama for donations, M&A, gift tax, and IRA conversion, prepared in accordance with USPAP and IRS requirements. AppraiseItNow appraises small businesses, partnerships, corporations, professional practices, and franchises across Alabama, including Birmingham, Huntsville, and Montgomery.

Get an instant response

DEFENSIBLE, USPAP-COMPLIANT BUSINESS APPRAISAL REPORTS — QUALIFIED FOR THE IRS, ALABAMA COURTS, LENDERS, INSURERS, AND MORE.

  • IRS
  • GASB
  • Alabama Courts
  • U.S. Small Business Administration
  • Chase
  • Regions Bank
  • Bank of America

Credentialed Appraisers Serving Alabama

Between them, our business valuation appraisers hold ASA, ABV, and CFA designations, and every report is written to USPAP for the IRS, Alabama courts, lenders, insurers, and more.

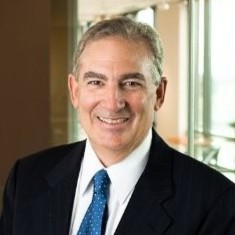
Joe Kattan

Joe Kattan

Owner & CEO

Joe founded AppraiseItNow to make a certified, USPAP-compliant appraisal as simple to order as anything else online. A former Bain & Company strategy consultant, Joe leads the entire team and specializes in strategy, growth, and the firm's tech capabilities.

Justin Ramirez

Justin Ramirez

Business Valuation Expert & Appraiser

ASA, ABV, and CFA charterholder. Since 2016 Justin has valued businesses for estate and gift tax, purchase price allocations, fairness opinions, lending, and buy-sell agreements, across manufacturing, services, retail, and pre-revenue biotech.

Raymond Ghelardi

Raymond Ghelardi

Business Valuation Expert & Appraiser

Accredited Senior Appraiser with the American Society of Appraisers. Raymond values capital stock, business enterprises, stock options, and intangible assets.

Aron Blue

Aron Blue

Client Success Manager

Manages each engagement from the first enquiry to the delivered report, and keeps you posted at every step along the way.

  • USPAPWritten to the Uniform Standards of Professional Appraisal Practice
  • American Society of AppraisersAccredited Senior Appraiser
  • AICPAAccredited in Business Valuation
  • CFA InstituteChartered Financial Analyst
  • The Appraisal FoundationAuthorized by Congress as the source of appraisal standards
What we value
Closely held interestsCorporations and S corporations, limited liability companies, partnerships, sole proprietorships, professional practices, and the minority and fractional stakes inside them.
Standard of value
Chosen by the filingA gift return, an estate schedule and a charitable gift of stock all ask for fair market value. A buyout or a court proceeding can ask for something else, and the report reconciles the two.
Where we start
The company's own fileSeveral years of returns and statements, the governing agreement, the ownership and distribution history, and the forecast the owners genuinely use to run the place.

Birmingham Manufacturers, Huntsville Contractors, and Mobile Family Corporations Are Alabama Companies We Value

AppraiseItNow appraises closely held Alabama companies, partnerships and professional practices for gift and estate tax returns, charitable gifts of stock or units, retirement account conversions, sales between owners, buy and sell agreements, and divorce. Where the balance sheet is mostly machinery, the equipment is valued in its own right by our Alabama equipment appraisals and the company conclusion is built on top of that.

Fractional stakes

An Alabama Minority Interest Is Defined by Its Agreement

Transfer restrictions, who controls distributions, and what a transferee actually receives are read out of the governing documents before any discount is discussed, because those terms are the evidence for it.

Professional practices

An Alabama Practice Earns Partly Through One Person

Where revenue follows a licensed owner, the valuation separates what the enterprise would keep from what would leave with that person, and says plainly which of the two it concluded on.

Earnings quality

An Alabama Company Is Priced on Earnings That Repeat

Owner perks, related party rent, single contracts that will not recur, and pay set for tax reasons are each adjusted and each shown, so a reviewer can disagree with one without rejecting the whole.

A Montgomery Buy Sell Agreement and a Tuscaloosa Succession File Both Start From One Alabama Valuation

An Alabama file usually names the day the value has to speak to, and that day is seldom the day we are asked. A gift return looks back to when the interest changed hands. A buy and sell agreement looks to the event that triggered it. An estate looks to the death. Fixing that first is what keeps later knowledge out of a conclusion that is not entitled to use it.

Hindsight

An Alabama Valuation Cannot Use What Nobody Knew Yet

A contract won two months after the date, or a customer lost just after it, is not evidence of value on the date. Such an event is disclosed as a later development instead of being priced in.

Control

Who Decides Is Worth More Than What Is Owned

Two Alabama stakes of identical size can be worth different amounts when one can force a sale or a distribution and the other cannot. The report names the powers the subject interest really carries.

Alabama Taxes a Company on Its Net Worth, and That Figure Is Not What the Company Is Worth

Two Alabama taxes land in the middle of a valuation. One is computed from a net worth figure owners regularly mistake for a value. The other moves income tax off the owners and onto the company, changing what reaches them.

Privilege tax

Net worth

is the Alabama business privilege tax base, graduated by the size of that net worth and capped by entity type

An Alabama Privilege Tax Return Reports Net Worth, Not Market Value

Alabama computes the business privilege tax on taxable Alabama net worth. The Department of Revenue's rate schedule runs from "$ .25 per thousand" at the bottom of the table to "$1.75 per thousand" at the top, with maximum amounts of "$15,000" for C corporations, S corporations, regulated utilities and real estate investment trusts, "$500" for an electing family limited liability entity, and "$3,000,000" for financial institution groups and insurance companies subject to the Alabama insurance premium tax. The same schedule records that under Act 2022-252, "for taxable year 2024, taxpayers who would be subject to the minimum tax of one hundred dollars ($100), do not have a filing requirement." Net worth here is a balance sheet figure assembled from historical cost. An owner who offers a privilege tax return as proof of what the company is worth is offering book value, which is where a great many Alabama valuation conversations have to start.

Alabama Department of Revenue, business privilege tax quick reference

Entity level tax

5 percent

is the Alabama rate an electing pass through entity pays on its own taxable income before anything reaches the owners

An Alabama Election Moves the Income Tax From the Owners to the Company

For tax years beginning on or after January 1, 2021 an Alabama S corporation or Subchapter K entity may elect to be taxed at the entity level. The Department of Revenue states the rate without qualification: "The tax rate is 5 percent." The entity's Alabama taxable income is apportioned under chapter 27 of Title 40, and the Department adds that "Alabama tax paid under this provision shall not be deducted in calculating Alabama taxable income," while each owner reports a distributive share and claims a refundable credit for the tax the entity paid. None of that is a detail for an appraiser. An electing company's historical cash flow carries a state tax its owners used to pay personally, so a benefit stream lifted straight from the statements of an electing year is not comparable with one from a year before the election, and whether the election is expected to continue is an assumption the report has to put in writing.

Alabama Department of Revenue, electing pass through entity FAQ

What clients say we are known for

AppraiseItNow Reviews: “The report was quite thorough as well” and “The team was highly knowledgeable, helpful, and efficient”

  1. Being the appraiser they come back to“I highly recommend their appraisal services, especially for private companies” Steve R.Mentioned in 51 reviews
  2. Answering fast, and staying reachable while the work runsMentioned in 40 reviews
  3. Showing the research and the comparables behind the number“Their work was quick, thorough” Jeff H.Mentioned in 34 reviews
  4. Delivering the finished report ahead of the deadlineMentioned in 28 reviews
  5. Taking on items other appraisers had already turned downMentioned in 15 reviews

Across 100+ published AppraiseItNow reviews the picture is consistent: every one is from a client who paid us for an appraisal, and the three things they raise most often are that they would hire us again, how quickly we answer, and how much research is visible in the report.

  • Responsive, professional, first class deliverables -- especially considering that that the appraised assets are extremely complex financial assets with little by way of comps. The deliverable satisfied my accountants and advisers as being more than adequate to support the valuation needed to complete a conversion to a Roth IRA
    Dave T. ·

    Business Valuation Appraisal for IRA Conversion

  • Joe and Aron were extremely impressive - the entire process went very smoothly. They were always quick to respond to any questions I had and could not have been more helpful. They were aware of some tight time restrictions I had and made sure I received my reports in a timely fashion. I highly recommend them to anyone needing a valuation.
    William L. ·

    Business Valuation Appraisal for Charitable Donation

  • I used AppraiseItNow to examine a contribution to a foundation. Their work was quick, thorough, and easy to work with, as they’ve developed a simple system for uploading documents. I plan to use them again.
    Jeff H. ·

    Business Valuation Appraisal for Charitable Donation

  • The team was highly knowledgeable, helpful, and efficient. I highly recommend their appraisal services, especially for private companies.
    Steve R. ·

    Business Valuation Appraisal for IRA Conversion

  • I found them professional & responsive. The report was quite thorough as well.
    Daniel L. ·

    Business Valuation Appraisal for Charitable Donation

  • From the start they were very responsive, price competitive, and had a quick turn around time. Thank you so much to Joe who was very sweet in responding to my emails; I am looking forward to utilizing AppraiseItNow for many years to come.
    Chris S. ·

AppraiseItNow delivers written business valuations for gift and estate tax, IRA conversions, charitable donations, and buy/sell agreements

Given the USPAP-compliant nature of AppraiseItNow’s appraisal reports, we prepare our deliverables for major legal, tax, and financial reporting purposes for individual and commercial clients.

Popular uses of our appraisal reports include:‍

Transactions, Lending & Investment

Frequently Asked Questions on Alabama Business Valuations

Which approaches apply when valuing an Alabama business?

The income, market, and asset-based approaches. Professional standards from the AICPA, ASA, NACVA, and the IRS Business Valuation Guidelines all direct the analyst to consider all three, then weight the methods that best fit the company; reviews commonly flag reports that fail to document why an approach was rejected.

Can an industry rule of thumb value my company for a legal matter?

No. NACVA's professional standards limit rules of thumb to reasonableness checks because a multiple of sales or EBITDA ignores earnings quality, growth, asset mix, and risk. Tax, divorce, and shareholder matters require analysis of actual financial statements, industry conditions, and comparable transactions.

How is a business valued in an Alabama divorce?

Alabama divides marital property by equitable distribution, and courts typically value assets as of the trial or final judgment date rather than the date of separation. That means a business valuation for an Alabama divorce generally needs to reflect conditions near the time of trial, though judges have discretion on the date.

What should the front of a business valuation report state?

The standard of value, the premise of value, the effective date, the exact interest being valued, and the information sources used. Standards require enough disclosure that a reader could follow the analysis from data to conclusion, which is what makes the report defensible under IRS or court review.