How are damages measured when memorabilia is damaged?
As the difference between the item's market value immediately before and immediately after the loss. If the piece is repairable, recovery is generally limited to the lesser of repair cost and that loss in value, with salvage credited. This before-and-after rule is the default for personal property claims unless the policy specifies another basis.
What if the damaged piece has no established market?
Many courts then allow recovery of its actual or intrinsic value to the owner, looking at original cost and replacement practicability, but most exclude purely sentimental value; New York expressly limits owners to actual monetary loss. Documenting whatever market exists, even a thin one, usually produces a stronger claim than arguing intrinsic value.
How do insurers treat damage to part of a set?
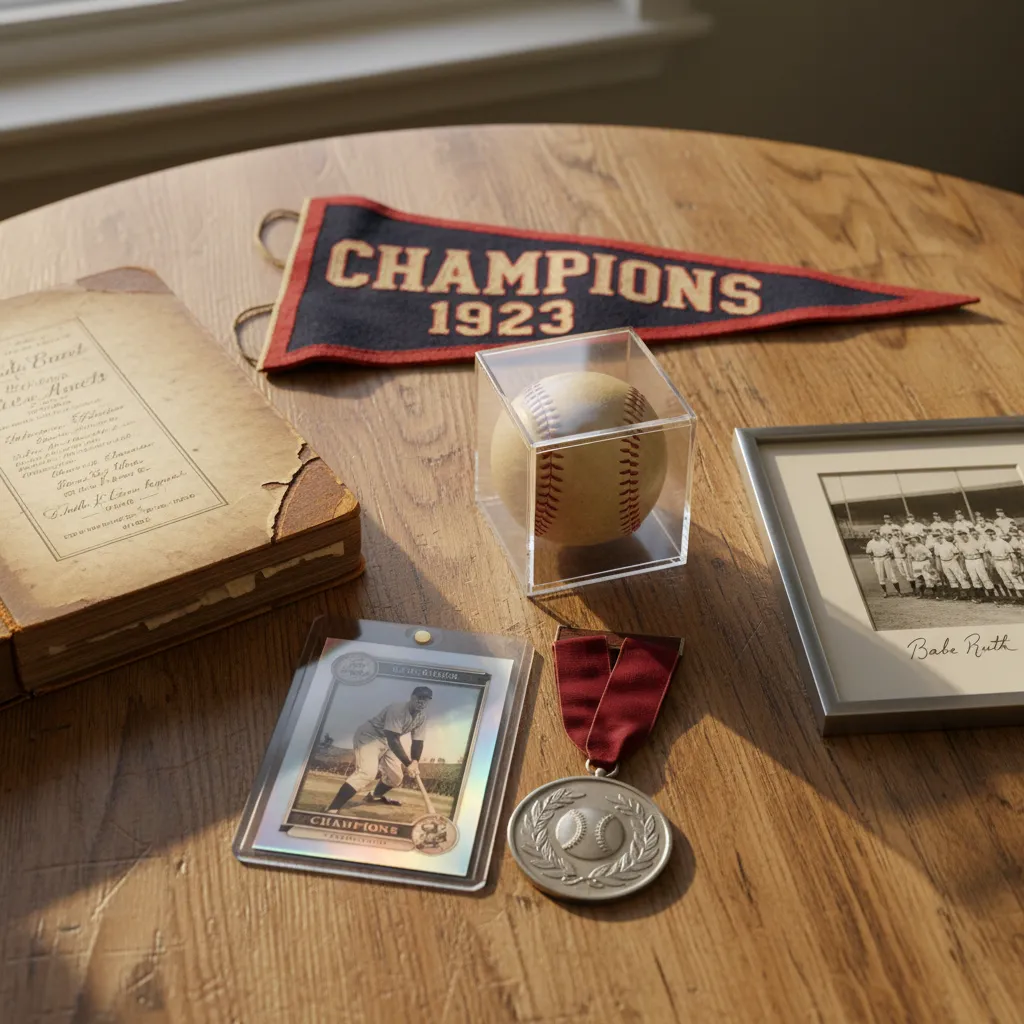
Item by item: adjusters value the damaged pieces under the policy's replacement cost, market value, or agreed value terms, and generally do not treat an incomplete set as a total write-off. Collectors who believe set cohesion drives the value need appraisal evidence quantifying how the set premium is destroyed by the damaged pieces.
Why does pre-loss documentation decide these claims?
Because value immediately before the damage must be proven with evidence contemporaneous to the loss date: condition records, provenance, catalog prices, auction results, and dealer listings. Payouts are also capped by policy limits and per-item schedules, so a well-documented pre-loss value is frequently the difference between market value and a sublimit payment.