
Wholesale Granite Donation Appraisal
Granite slab appraisal for charitable donation substantiation, covering new commercial stone inventory, palletized slab bundles and material destined for wholesale rather than retail channels. AppraiseItNow appraised a Texas donation of new, unused commercial granite slabs, researching industrial auction and wholesale liquidation evidence for the quantity actually transferred.
Project Overview
Assignment Summary
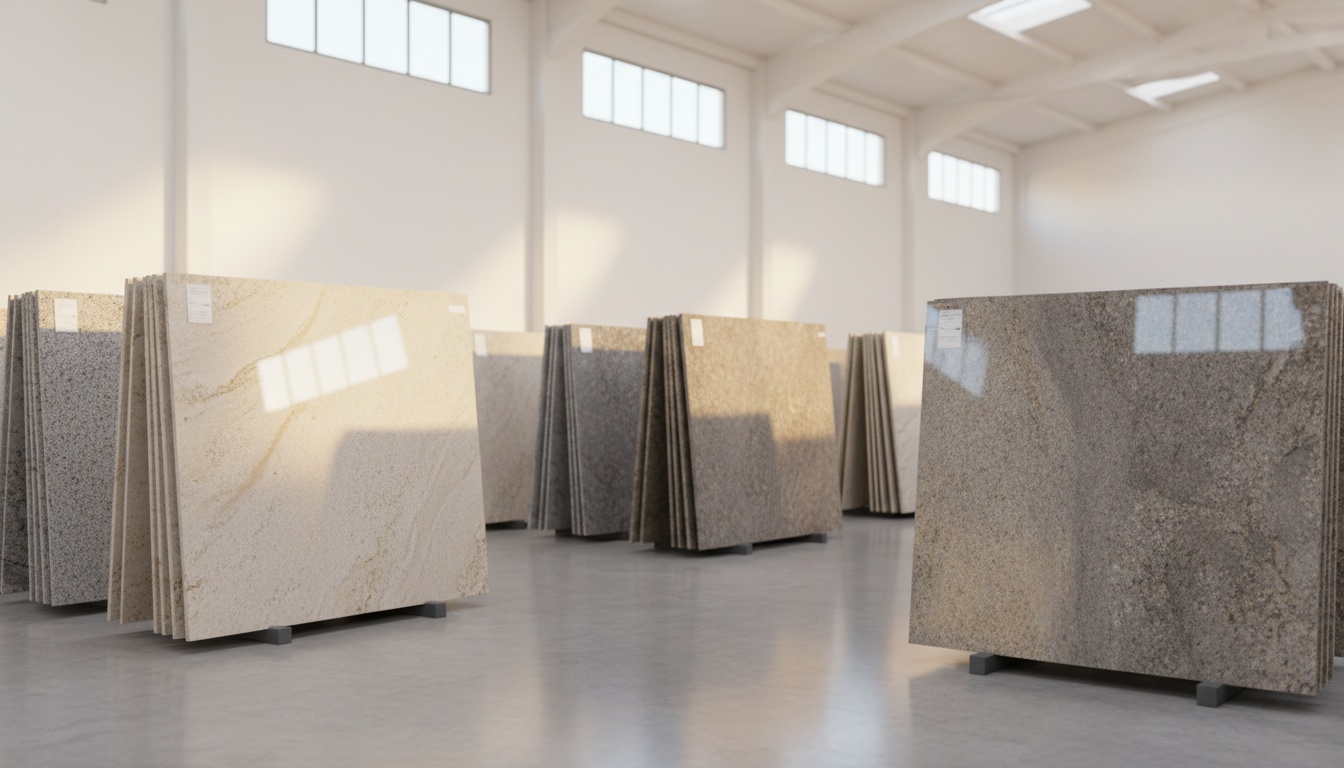
The scope of work covered identification and examination of the property through photographs and owner-provided information, market research for comparable wholesale transactions, and analysis to reach a fair market value conclusion. The subject assets consisted of a large quantity of new, unused commercial granite slabs intended for wholesale markets rather than retail consumer sales. The appraisal was developed and reported using the Appraisal Report option under USPAP and conforms to IRS guidance for charitable contribution substantiation. The intended use was limited to support the donor's non-cash charitable contribution, with the report prepared for the donor, the donee organization, and tax authorities only. The appraiser also completed the designated section of the donation form to assist the donor with filing requirements.
Challenges
Our Approach
Project Outcome
Ready to start your appraisal?
Tell us the asset and what the value is for, and we will confirm scope, timing, and a fixed fee before any work begins.
Request an AppraisalFrequently Asked Questions
Why is donated granite valued at wholesale rather than fabricated countertop prices?
Because a slab is not a countertop. Installed countertop pricing includes templating, fabrication, edge work, transport and installation, which are services the donor did not contribute. The donated property is raw material, and its market is the wholesale and liquidation channel where fabricators and distributors buy slabs by the bundle.
Does color and pattern affect the value of commercial stone?
Considerably. Granite pricing varies by quarry, color group, pattern consistency and thickness, and demand for specific colors shifts with design trends. Two pallets of the same nominal square footage can differ substantially in value depending on the material. Identifying the stone type is part of establishing the value, not a descriptive detail.
How are slab counts verified for a donation?
From the owner's records and representative photographs, with the basis stated. Slabs stored in A-frame racks or banded bundles cannot be individually counted without handling equipment, so the appraisal relies on documented inventory and states that as an extraordinary assumption. Donors who photograph and count the bundles before transfer remove the issue.
Does damage to a slab remove its value entirely?
Not entirely, but cracked or chipped slabs drop sharply because fabricators plan yields around full sheets. Damaged material can still be cut into smaller pieces for vanities, thresholds and remnant work, which retains some value. Where damage was visible in the documentation it is noted; where slabs were not individually inspected, the report says the condition rests on the owner's representation.