
Valuing Medical Equipment in a Bankruptcy Liquidation
Medical equipment appraisal for a bankruptcy liquidation, covering surgical, imaging, sterilization and recovery equipment valued at net forced liquidation value. AppraiseItNow appraised approximately 73 pieces of California surgical center equipment including OR tables, anesthesia machines, C-arm imaging and sterilizers, pricing an immediate as-is, where-is disposition with no marketing budget.
Project Overview
Assignment Summary
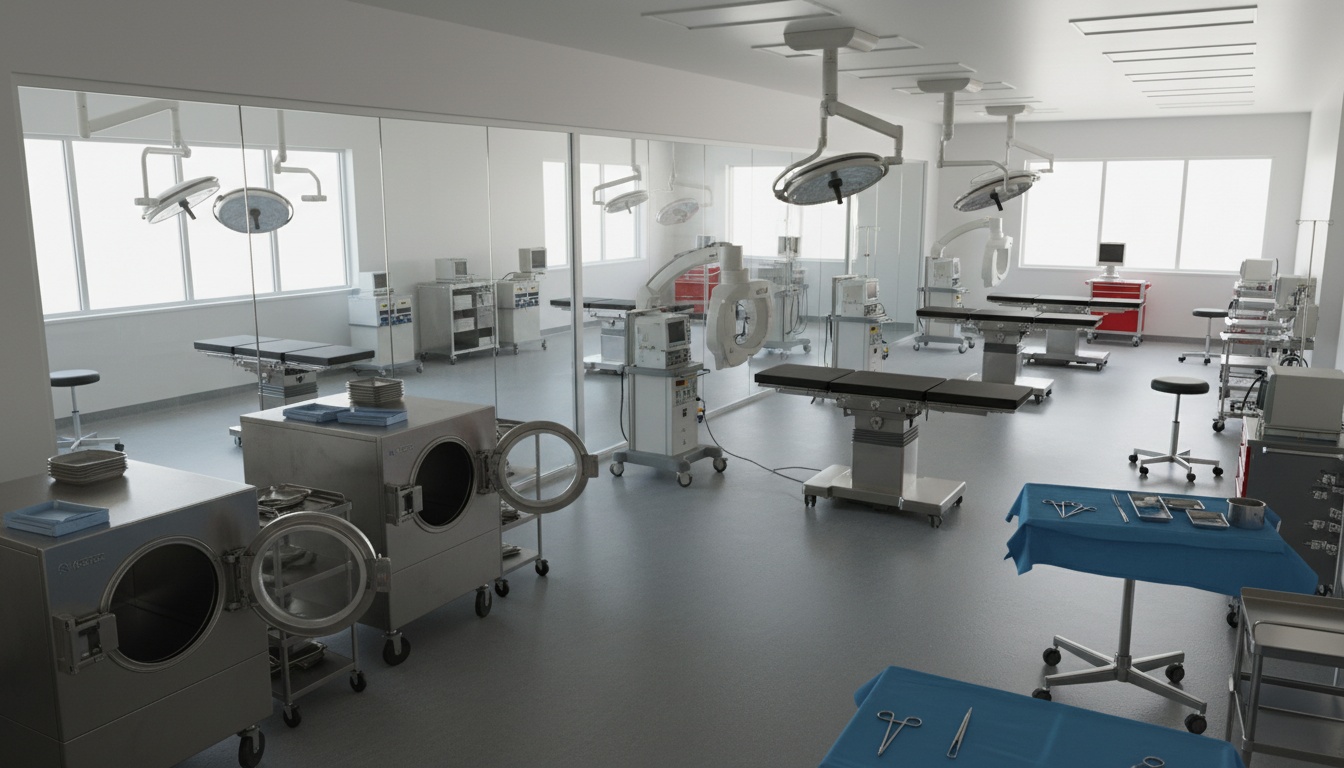
The subject assets consisted of approximately 73 pieces of medical equipment spanning surgical, imaging, sterilization, and recovery categories. The inventory included OR tables, anesthesia machines, electrosurgical units, C-arm imaging systems, sterilization equipment, surgical instruments, patient monitors, recovery stretchers, crash carts, and a variety of ancillary items. Much of the equipment had been in service since the mid-2000s. The required standard of value was Net Forced Liquidation Value — the estimated amount realizable under an immediate, compelled sale on a strict as-is, where-is basis, with no representations or warranties. The appraisal was completed in conformity with the 2024 Uniform Standards of Professional Appraisal Practice (USPAP) and was intended to support a Chapter 7 bankruptcy filing, with the report delivered to the client and relevant bankruptcy representatives.
Challenges
Our Approach
Project Outcome
Ready to start your appraisal?
Tell us the asset and what the value is for, and we will confirm scope, timing, and a fixed fee before any work begins.
Request an AppraisalFrequently Asked Questions
What is net forced liquidation value?
It is the amount realizable from an immediate, compelled sale on an as-is, where-is basis, net of the costs of disposal. It assumes no marketing period, no reconditioning and no ability to wait for the right buyer. It is the lowest of the common value premises and is used where an estate has no budget or time to conduct an orderly sale.
Why does the absence of a marketing budget lower the conclusion so much?
Because exposure to the market is what produces competitive bidding. Without advertising, listing, storage or the ability to hold assets until buyers appear, the estate is selling to whoever is present, and prices reflect that. Equipment that would bring a solid figure over a 90-day orderly sale can bring a fraction of it when it must move immediately or be abandoned.
Does older surgical equipment retain value in a liquidation?
Some categories do better than others. Sterilizers, OR tables and basic surgical instruments have durable demand and simple maintenance; imaging systems and anesthesia machines carry service, software and regulatory dependencies that narrow the buyer pool sharply once support ends. Equipment in service since the mid-2000s is generally at the point where those dependencies dominate.
How does an appraiser handle 73 assets in a distressed timeline?
By valuing at the lot and category level with individual treatment for the items that carry material value. In a forced liquidation the estate is usually selling in bulk anyway, so a valuation structured around realistic sale lots is more useful than one that prices each item as if it would find its own buyer. The report explains the lotting assumption.