
Valuing a Minority LLC Interest for IRA Conversion

Minority LLC interest valuation for IRA conversion, covering single-asset real estate entities, HUD-subsidized multifamily property and non-controlling membership units. AppraiseItNow valued a 6.0% membership interest in an Illinois LLC holding a 168-unit apartment complex near Peoria, applying a multi-period discounted cash flow analysis to an entity with an established operating history.
Valuing a Minority LLC Interest for IRA Conversion

Project Overview

AppraiseItNow was engaged to determine the fair market value of a minority membership interest in a closely held limited liability company that owns and operates a multifamily residential apartment complex in central Illinois. The assignment was prepared for IRS tax purposes in connection with an IRA conversion, requiring a rigorous and fully defensible valuation opinion. The subject interest represented a 6.0% non-controlling, non-marketable stake in the LLC, and the engagement demanded careful analysis of both the underlying business and the applicable valuation discounts. The valuation was conducted in conformity with USPAP, the American Society of Appraisers Business Valuation Standards, and the requirements of IRS Revenue Ruling 59-60.

Assignment Summary

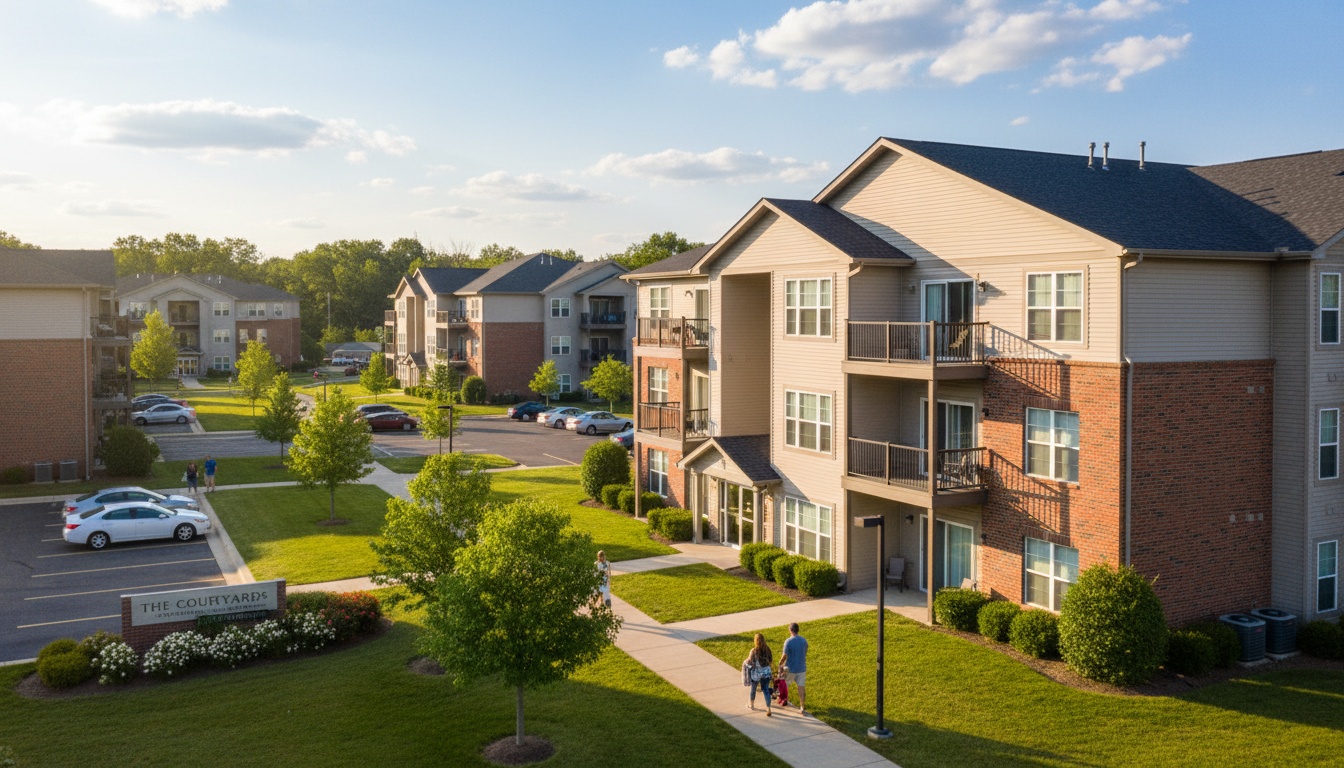
The subject entity is a closely held LLC whose sole asset is a large multifamily apartment complex consisting of 168 units across multiple buildings in a suburb of Peoria, Illinois. The unit mix spans studios, one-, two-, and three-bedroom apartments, with a portion operating at market-rate rents and the majority subsidized through U.S. Department of Housing and Urban Development (HUD) programs. The LLC has owned and operated the property since 2018, with day-to-day management handled by an established regional property management company. The assignment required valuing a 6.0% membership interest on a non-controlling, non-marketable basis, taking into account the rights and restrictions set forth in the LLC's operating agreement. The applicable standard of value was fair market value as defined under Treasury Reg. §20.2031-1(b), and the intended users included the client, their relevant agents and representatives, and the Internal Revenue Service.

Challenges

One of the primary challenges in this engagement was the limited reliability of the Market Approach, which was ultimately not applied. Because the LLC owns a single income-generating property, it was difficult to identify sufficiently comparable guideline public companies or transaction data — publicly traded real estate entities were far larger and more diversified, and available M&A transaction data was either incomplete or drawn from pre- or post-COVID periods that limited meaningful comparability. An additional layer of complexity stemmed from the fact that approximately 61% of the apartment units are subsidized through HUD programs, which restricts the LLC's ability to raise rents in line with local market conditions — a nuanced factor requiring careful consideration in both the income forecast and the application of valuation discounts. Determining the appropriate discounts for lack of control and lack of marketability also required extensive analysis, drawing on multiple empirical studies while carefully weighing company-specific characteristics such as the concentrated single-asset portfolio, distribution history, and the unique limitations imposed by HUD rent restrictions.

Our Approach

Given the LLC's established history of positive cash flows and the expectation of continued earnings growth, the Income Approach was selected as the most appropriate and reliable method, with a multi-period discounted cash flow (DCF) analysis applied using debt-free net cash flow as the income stream. Historical audited financial statements spanning several fiscal years were carefully analyzed and normalized to account for recurring repair costs that could reasonably be capitalized on a forward-looking basis. The weighted average cost of capital (WACC) was developed by screening publicly traded real estate companies and building up relevant risk factors, and a terminal growth rate was applied consistent with long-term projections for real GDP growth and inflation. To arrive at the fair market value of the minority interest, the indicated enterprise value was adjusted for net working capital and then subjected to both a discount for lack of control and a discount for lack of marketability, each supported by a thorough review of empirical studies — including Partnership Profiles, Inc. partnership data and a closed-end fund discount analysis — and company-specific considerations. A third-party real estate appraisal of the underlying property was also incorporated by reference to support the overall analysis.

Project Outcome

The engagement produced a well-supported, USPAP-compliant appraisal report suitable for IRS submission, giving the client and their advisors a credible and defensible fair market value conclusion grounded in rigorous financial analysis and empirical discount studies — providing a reliable basis for completing the tax reporting requirements associated with the IRA conversion.

Ready to start your appraisal?

Tell us the asset and what the value is for, and we will confirm scope, timing, and a fixed fee before any work begins.

Request an Appraisal

Frequently Asked Questions

Why use an income approach for a single-property real estate LLC?

Because the entity has a demonstrated history of positive cash flow and an expectation of continued earnings, which is exactly what a discounted cash flow analysis measures. A holding entity with only nominal income would call for a net asset value method instead. The approach follows the entity's economics rather than its asset type.

How does HUD subsidy affect the valuation of an apartment property interest?

It changes both the revenue profile and the risk profile. Subsidized units carry contractual rent support that reduces collection and vacancy risk, and they also carry regulatory obligations, compliance costs and restrictions on rent growth and disposition. A responsible analysis models the subsidized and market-rate portions separately rather than blending them into one assumption.

Why was the market approach not used here?

Because a single-property LLC has no meaningful guideline public company set and few comparable entity transactions. Public real estate companies are diversified and professionally capitalized in ways this entity is not, and forcing their multiples onto it would import risks and advantages that do not apply. The report explains the exclusion rather than silently omitting the approach.

Does an IRA conversion valuation need to consider the property's own appraisal?

It should reference one where the analysis depends on asset value, and it usually does even under an income approach, as a cross-check on the entity conclusion. A current real estate appraisal of the complex is the strongest support available. Where the analysis relies on one, the report identifies it and its date rather than treating the property value as an input without a source.