
Valuing a Family LLC for Estate Planning

Family LLC valuation for estate planning, covering land-holding entities, timber and recreational acreage, and membership units held across family trusts. AppraiseItNow valued a single membership unit in a Georgia family LLC holding a rural tract of planted longleaf pine and natural woodland, applying the net asset value method to an entity with only nominal income.
Valuing a Family LLC for Estate Planning

Project Overview

AppraiseItNow was engaged to determine the fair market value of a minority membership interest in a closely held family limited liability company formed to hold and manage real property. The company's primary asset was a rural timber and recreational land tract, and the appraisal was prepared in connection with estate tax planning and the transfer of membership units to trusts established for the owners' children. The engagement required a highly technical analysis of a non-controlling, non-marketable interest in a newly formed entity with limited operating history. The appraisal was developed in conformity with USPAP, the American Society of Appraisers Business Valuation Standards, IRS Revenue Rulings 59-60 and 93-12, and the AICPA Statement on Standards for Valuation Services.

Assignment Summary

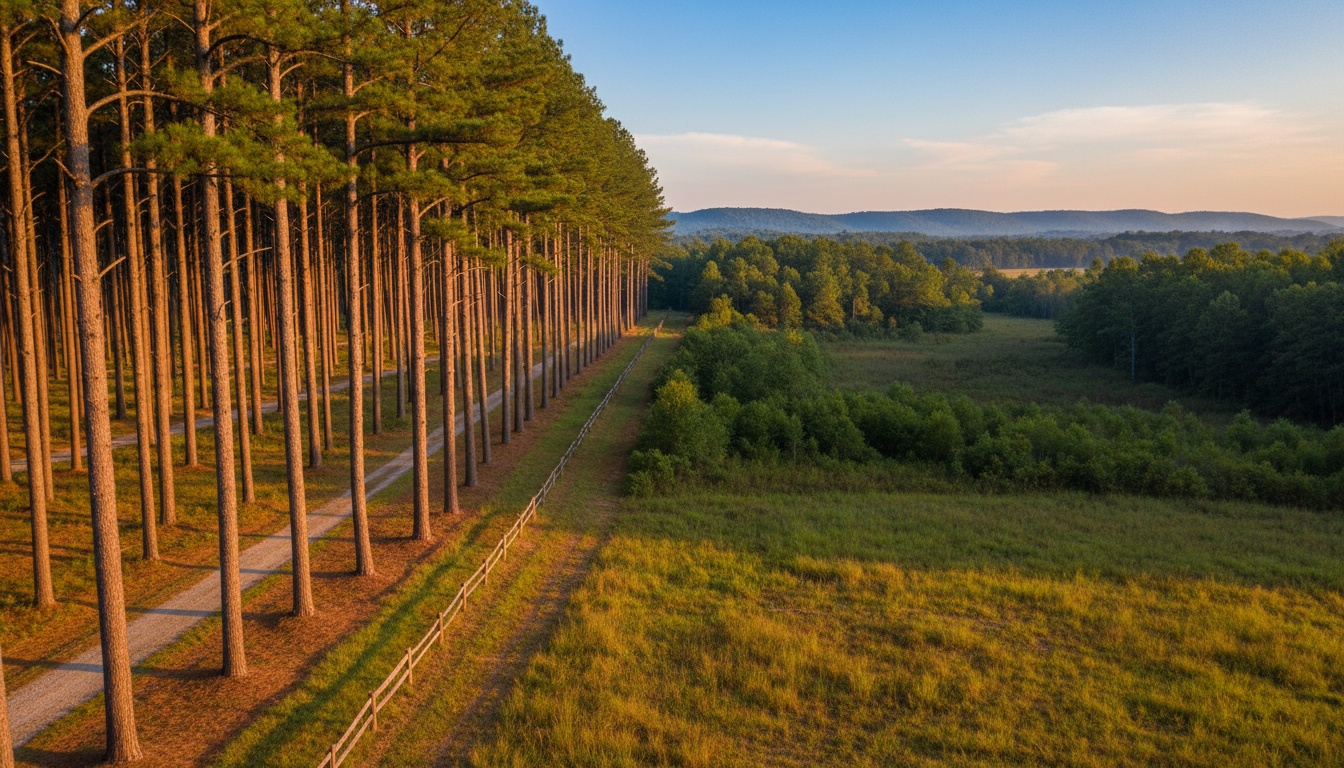
The subject of this appraisal was a single membership unit in a newly formed family LLC structured as a holding entity for a rural land tract in central Georgia. The property consists primarily of planted longleaf pine timber acreage, natural woodland, and wet areas used for recreational and timber production purposes. The company was formed to centralize family asset management, prevent fractionalization of ownership, and facilitate long-term wealth transfer. Ownership was equally distributed across three trusts, each holding an identical block of units, with each trust benefiting one of the owners' children. The appraisal was intended for use by the clients, their representatives, and the IRS in connection with estate tax planning and the gifting of membership units, with fair market value determined consistent with the willing buyer and willing seller standard under Treasury Regulation §25.2512-1.

Challenges

One of the primary challenges in this engagement was the company's very limited income-generating capacity, which effectively ruled out the use of an Income Approach or earnings-based Market Approach methods. The property produced only a nominal hunting lease income that, after accounting for property taxes and mortgage debt service, resulted in a near-zero net yield — making cash flow-based valuation entirely unsuitable. Because the company was newly formed, there was no established operating history, no distribution record, and no finalized balance sheet as of the valuation date, requiring the appraiser to reconstruct a market value balance sheet in close coordination with management. Determining appropriate discounts for lack of control and lack of marketability also required careful judgment, as the company's concentrated single-asset portfolio and highly restrictive transfer provisions under the operating agreement presented characteristics that did not map neatly onto any single empirical study.

Our Approach

Given that the LLC functioned as a real estate holding company with no meaningful income-generating activities, the Asset Approach was selected as the primary valuation methodology — specifically, the Net Asset Value (NAV) method. The market value of the underlying real property was sourced from a third-party real estate appraisal prepared by an independent firm, and the outstanding mortgage liability was adjusted to its estimated market value to arrive at a controlling, marketable equity value for the company. To convert this to a non-controlling, non-marketable basis, two sequential discount analyses were conducted. For the Discount for Lack of Control (DLOC), the appraiser analyzed minority interest data from Partnership Profiles, Inc. focused on real estate partnerships, as well as a closed-end fund discount study using the TagniFi platform, with the concluded discount reflecting a blend of both sources adjusted for company-specific factors. For the Discount for Lack of Marketability (DLOM), the appraiser drew on a comprehensive review of restricted stock and pre-IPO studies, as well as the Mandelbaum factors established by the U.S. Tax Court, with the final discount reflecting the company's long anticipated holding period, absence of distributions, transfer restrictions, and limited management resources.

Project Outcome

The appraisal delivered a well-supported, IRS-compliant fair market value conclusion for both a single membership unit and for the equal unit blocks held by each of the three member trusts. The report gave the clients and their advisors a clear, defensible basis for the gifting of company units, supporting an orderly and tax-efficient intergenerational wealth transfer strategy for the family.

Ready to start your appraisal?

Tell us the asset and what the value is for, and we will confirm scope, timing, and a fixed fee before any work begins.

Request an Appraisal

Frequently Asked Questions

Why is the asset approach used for a family land-holding LLC?

Because the entity's value comes from what it owns rather than what it earns. A holding company with only nominal lease income has no meaningful earnings stream to capitalize and no comparable operating companies to draw multiples from, so the net asset value method is the appropriate primary approach. The report explains why the income and market approaches were considered and set aside.

What discounts apply to a minority unit in a family LLC?

A discount for lack of control and a discount for lack of marketability, quantified separately. A member holding a non-controlling block cannot force a sale of the land, compel distributions or amend the operating agreement, and there is no market in which the unit can be sold. Both discounts are supported from empirical data and from the specific restrictions in the governing documents.

Does the underlying land need its own appraisal?

Yes, and the entity valuation depends on it. Under a net asset value method the real property value is the principal input, so it should come from a qualified real estate appraisal of the tract rather than a tax assessment or an owner estimate. Timber acreage in particular may warrant a separate timber cruise, since standing timber value can differ sharply from raw land value.

How does the operating agreement affect the value of a family LLC unit?

Directly and substantially. Transfer restrictions, rights of first refusal, distribution policy, dissolution terms and any buy-sell formula all shape what a hypothetical buyer of the unit would receive and how easily they could exit. Reading the agreement is not preliminary work in these engagements; it is where the discount analysis comes from.